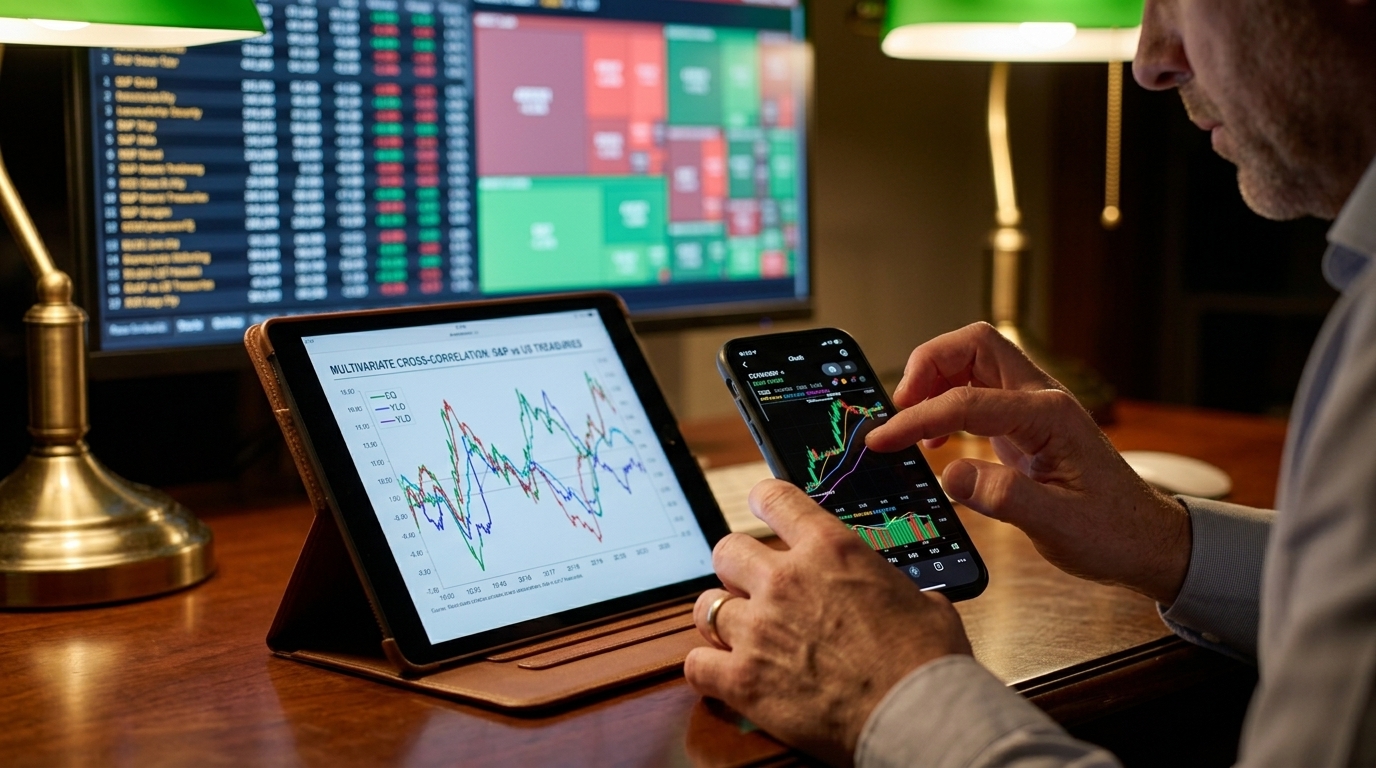
For decades, the investment world operated under a simple, almost axiomatic assumption: when stocks fall, bonds rise. This inverse correlation was the bedrock of the famous "60/40" portfolio, providing a safety net for investors during market turbulence. However, as we move through 2026, this "enigma" of both asset classes moving in tandem—either up or down—has shifted from a temporary anomaly to a persistent and troubling new reality. The return of capital scarcity is fundamentally altering the financial landscape.
The End of the "Free Money" Era
The last fifteen years were defined by an unprecedented period of low, and even negative, interest rates. Central banks, in their bid to stimulate economies following the 2008 crisis and the global pandemic, flooded markets with liquidity. In this environment, capital was abundant and cheap. Investors didn't need to be particularly selective; almost every asset class appreciated. Today, the script has flipped. Inflation, though stabilized compared to the 2022-2023 peaks, remains a structural threat, forcing central banks to maintain interest rates at levels not seen since the turn of the century.
Capital scarcity means that money now has a cost. This cost acts as gravity for stock valuations, particularly for growth and tech companies that rely on future cash flows. Simultaneously, bonds, once considered the ultimate safe haven, have become a source of volatility. When inflation is the primary market driver, stocks and bonds tend to move in the same direction, exposing investors to risks they thought they had hedged against.
The Return of Fundamentals
In this new environment, fundamental analysis is making a grand comeback. It is no longer enough to simply "buy the dip." Investors are required to look deeper into profitability, debt management, and a company's ability to generate free cash flow in a high-rate environment. Bonds, on the other hand, now offer attractive yields, creating stiff competition for equities. Why take the risk of the stock market when one can secure a guaranteed 4% or 5% return from government treasuries?
- Correlation between asset classes remains positive as long as inflation stays above central bank targets.
- Sovereign debt levels in major economies (US, Eurozone) are putting pressure on bond markets, driving yields higher.
- Institutional investors are increasingly pivoting toward alternative investments, such as private equity and real estate, to find true diversification.
"The illusion of eternal liquidity has vanished. We are now facing a reality where capital must be earned, not just printed." — International Market Analyst
Political Implications and Geopolitical Uncertainty
The enigma is not merely economic; it is deeply political. The rise of protectionism and ongoing geopolitical tensions in Ukraine, the Middle East, and Taiwan impact supply chains and, by extension, inflation. Governments, in their rush to fund the green transition and defense budgets, are issuing massive amounts of debt. This oversupply of bonds, occurring just as central banks are shrinking their balance sheets (quantitative tightening), creates a profound supply-demand imbalance.
For the Eurozone, the challenge is twofold. The need for fiscal discipline clashes with the urgent requirement for investment in innovation and security. Borrowing costs for member states remain highly sensitive to ECB policy shifts, as the bank attempts to balance inflation control with the avoidance of a deep recession. The bond-stock enigma will continue to haunt investors as the global economy searches for a new equilibrium, far removed from the extremes of the previous decade.