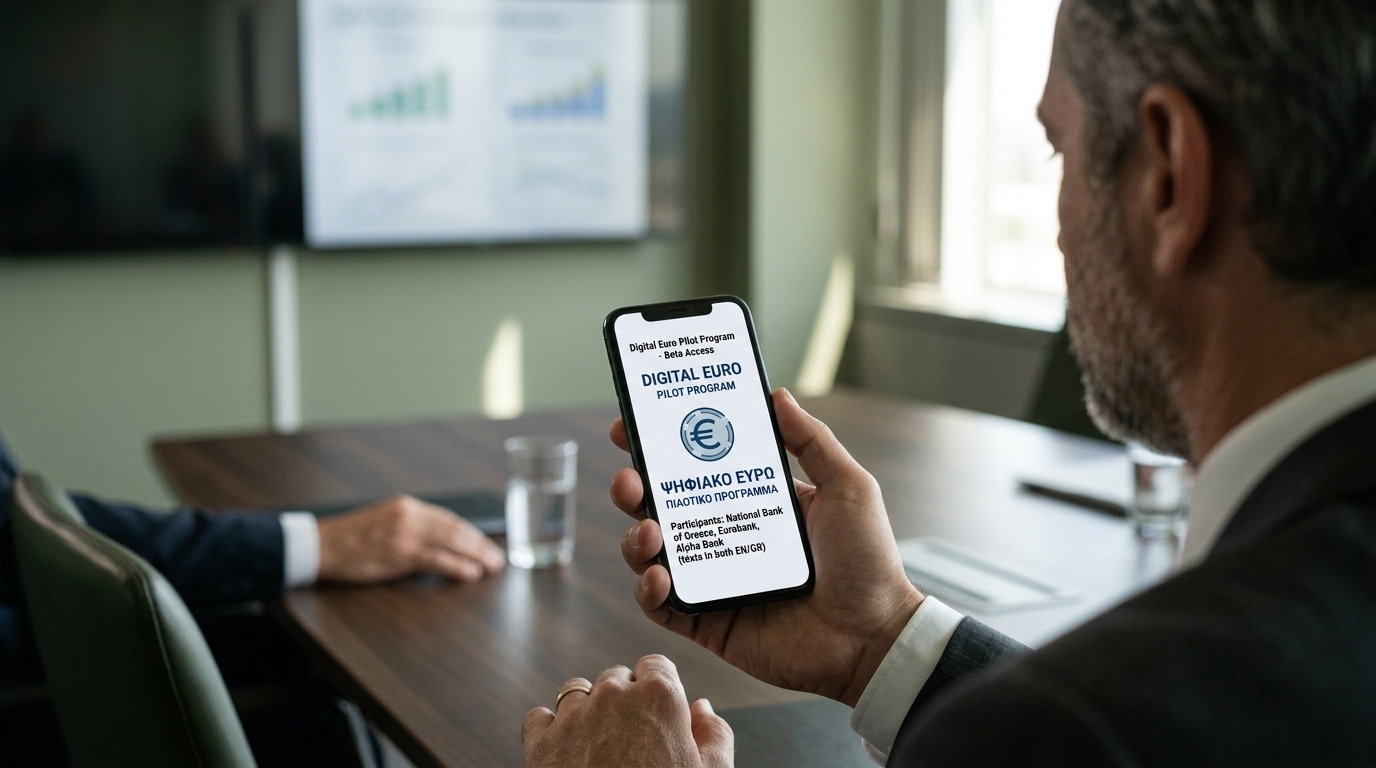
The countdown for the introduction of the digital euro has begun, with a pilot program scheduled to launch in the second half of 2027. The European Central Bank (ECB) aims for a wider rollout of this new European payment medium by 2029. A total of 36 providers from 19 countries will participate in these trials, including three Greek institutions: Piraeus Bank, National Bank of Greece, and Chania Bank.
How the Digital Wallet Will Function
The digital euro will be a digital form of the single currency, backed by the Eurosystem, and should not be confused with cryptocurrencies. Citizens will be able to use it via a digital wallet for daily transactions in physical stores, online shopping, and person-to-person money transfers.
A critical feature of the system is the ability to conduct offline transactions. This ensures accessibility even during technical failures or internet outages, while also enhancing privacy; in offline payments, transaction details remain known only to the payer and the payee.
Holding Limits and Financial Stability
To safeguard the stability of the banking system, the ECB is considering a holding limit of between €3,000 and €4,000 per citizen. This measure is designed to prevent massive outflows of deposits from commercial banks into digital wallets, particularly during times of financial uncertainty. Notably, these digital holdings will not accrue interest.
If a transaction exceeds the digital wallet's balance, the system will allow for the automatic coverage of the difference from the user's linked bank account, eliminating the need to manually "top up" the wallet before every purchase.
Strategic Autonomy and Privacy
Bank of Greece Governor Yannis Stournaras has emphasized that the digital euro is designed to complement cash, not replace it. Furthermore, the initiative aims to bolster Europe's strategic autonomy by reducing dependence on international payment networks like Visa and Mastercard, providing a public pan-European infrastructure instead.