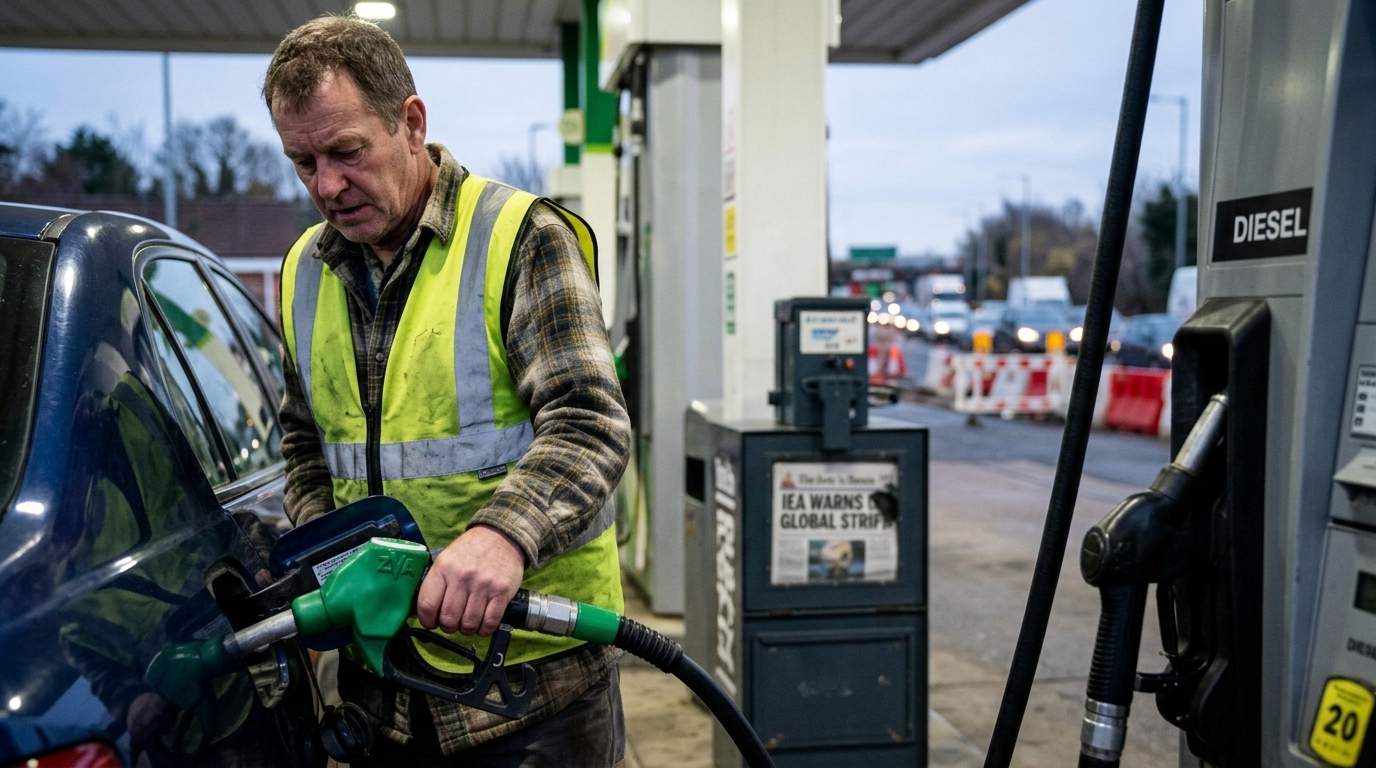
Global energy security is at one of its most critical junctures in recent history, as ongoing geopolitical conflicts violently reshape the map of supply and demand. According to the latest report from the International Energy Agency (IEA), the market for refined products—primarily gasoline and diesel—faces an existential risk of shortages, no longer driven solely by a lack of crude oil, but by the inability of infrastructure to withstand the pressures of war.
The Middle East Chessboard and the Threat to Sea Lanes
The escalation of tensions in the Middle East, the heart of global energy production, has created a climate of uncertainty that markets are struggling to fully price in. Attacks on tankers in the Red Sea and the looming threat of a closure of the Strait of Hormuz have forced logistics companies to opt for longer, more expensive routes around the Cape of Good Hope. This delay in fuel delivery not only increases shipping costs but also ties up vast quantities of product "at sea," reducing available inventories at terminals in Europe and Asia.
As the IEA points out, Europe's reliance on diesel imports from the Middle East and India has surged following the imposition of sanctions on Russian oil. Any disruption in these flows immediately translates into a supply crisis for European transport and industry, which rely on diesel as the primary "fuel of movement" for their economies.
The Refinery War: Russia Under Siege
On the other major front, the conflict in Ukraine has entered a new, more dangerous phase for energy infrastructure. Continuous drone attacks on Russian refineries have significantly hampered Moscow's ability to process crude oil and export finished products. Despite the fact that Russia remains one of the world's largest crude producers, the loss of its refining capacity creates a void in the global diesel market.
The IEA highlights that repairing these units is time-consuming and technically difficult due to Western sanctions on high-tech components. This means that the deficit in diesel supply is not transient but is becoming a structural feature of the market for 2026. The shortage of Russian diesel affects not only Europe but also emerging markets in Africa and Latin America, which are now competing for the same limited cargoes from the US and the Middle East.
The Structural Refining Crisis and Consumer Impact
Beyond the wars, the global refining industry is in a transition phase that exacerbates the problem. Many older refineries in the West have closed or been converted into biofuel plants as part of the green transition. At the same time, new large-scale facilities being built in China and the Middle East are facing delays in becoming operational.
"The fuel market is more vulnerable than ever, as the safety margin has been eroded. Every technical failure or geopolitical incident now triggers violent price spikes," the IEA report states.
For the average consumer, this translates into persistently high prices for gasoline and diesel, which in turn fuel inflation. The cost of transporting goods is rising, airlines are imposing fuel surcharges, and household purchasing power is shrinking. The IEA calls on governments to maintain high strategic reserves and prepare for potential fuel rationing if the situation in the Middle East spirals out of control.
Conclusions and Outlook
The IEA's warning is not just an economic analysis but an alarm bell for policymakers. The energy transition, while necessary, seems to coincide with a period of extreme geopolitical instability that makes traditional fossil fuels more valuable and simultaneously more inaccessible. The global economy is called upon to balance on a tightrope, where security of supply clashes with the need for low prices and environmental protection. The summer of 2026 promises to be hot, not just due to the climate, but due to developments on the war fronts that dictate the price of energy.