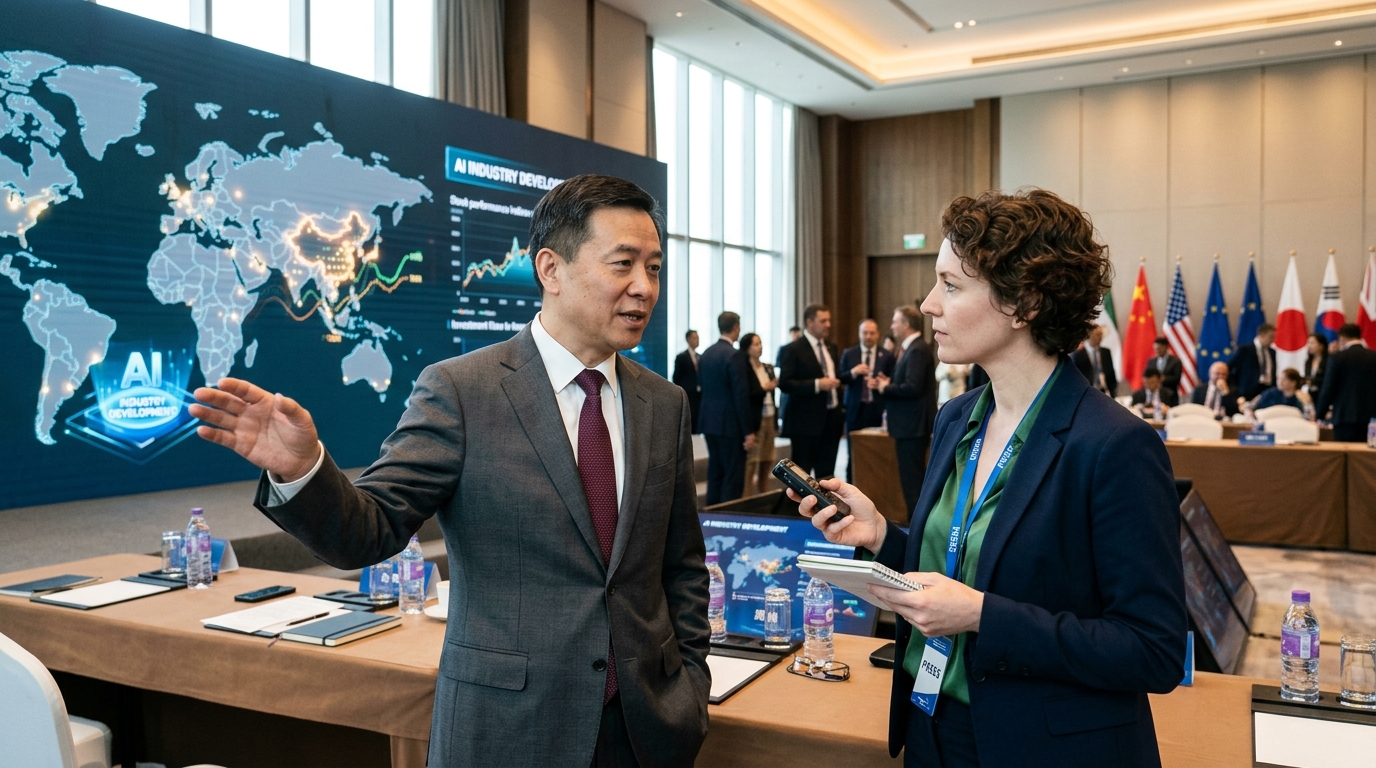
The history of financial markets is often a story of shifts. As we move through the summer of 2026, the euphoria that characterized Wall Street over the past two years—fueled by the likes of Nvidia and Microsoft—seems to be giving way to a more cautious, analytical approach. However, for those seeking the next phase of the Artificial Intelligence (AI) revolution, the gaze is no longer fixed on Silicon Valley, but on the other side of the Pacific. China, despite stringent U.S. export controls and domestic regulatory hurdles, is emerging as the new magnet for capital seeking the "next big leg up."
The Great Valuation Divergence
The primary driver of this rotation is simple and economic: valuation. While U.S. tech giants are trading at earnings multiples reminiscent of the dot-com era, Chinese titans such as Baidu, Alibaba, and Tencent have long remained on the sidelines, penalized by political risk and China's broader economic slowdown. But the fundamentals have begun to shift. The Chinese AI market is no longer a promise; it is a reality with hundreds of millions of active users and integrated industrial applications.
Analysts point out that the "value gap" between the U.S. Magnificent Seven and their Chinese counterparts has reached historic highs. This creates a unique opportunity for institutional investors looking for Growth at a Reasonable Price (GARP). Baidu, for instance, with its Ernie Bot ecosystem, has successfully integrated generative AI across its search and cloud business, showcasing adoption rates that have consistently outperformed market expectations.
The Strategy of "Sovereign AI" and Self-Reliance
China is not merely following the West's lead; it is building a parallel universe. The strategy of "Sovereign AI" has become the cornerstone of Beijing's national policy. Following the blockade of advanced Nvidia chips, Chinese firms were forced to innovate at the software and architecture levels. Huawei and SMIC have made significant strides in domestic semiconductor production, while models like Alibaba’s Qwen demonstrate that the Chinese language and local data environment provide a "moat" against Western competition.
Furthermore, the Chinese government, after a period of intense regulatory crackdowns on the tech sector, now appears to be adopting a more supportive stance. The realization that AI is the key to global power is driving subsidies, tax breaks, and, most importantly, a clear regulatory framework. While strict regarding content, this framework provides the stability necessary for long-term institutional investment.
Geopolitics and Risk: The Elephant in the Room
Naturally, investing in China is not without its perils. The U.S.-China geopolitical rivalry remains the ultimate wildcard. Export restrictions on technology and potential sanctions on capital flows are persistent threats. However, many fund managers argue that this risk is already baked into the share prices. "When you are buying Alibaba at one-fifth the valuation of Amazon, you are already paying for the geopolitical risk," noted one Hong Kong-based market strategist.
The question for 2026 is whether China can translate its technological prowess into sustainable profits. The adoption of AI in manufacturing, logistics, and healthcare in China is progressing at a faster clip than in the West, largely due to the centrally directed nature of its economy. This "real-world" application of AI in production is what excites investors even more than consumer-facing chatbots.
Conclusion: A Bipolar Tech World
The AI rally is not ending; it is evolving. From a one-horse race (USA), we are moving into a two-player marathon. Investors who ignore Chinese progress risk missing a significant portion of future global growth. China is no longer the "copycat" but an equal player defining its own rules in the game of machine intelligence. The shift of capital toward the East is the natural consequence of a market seeking equilibrium between innovation and value.