

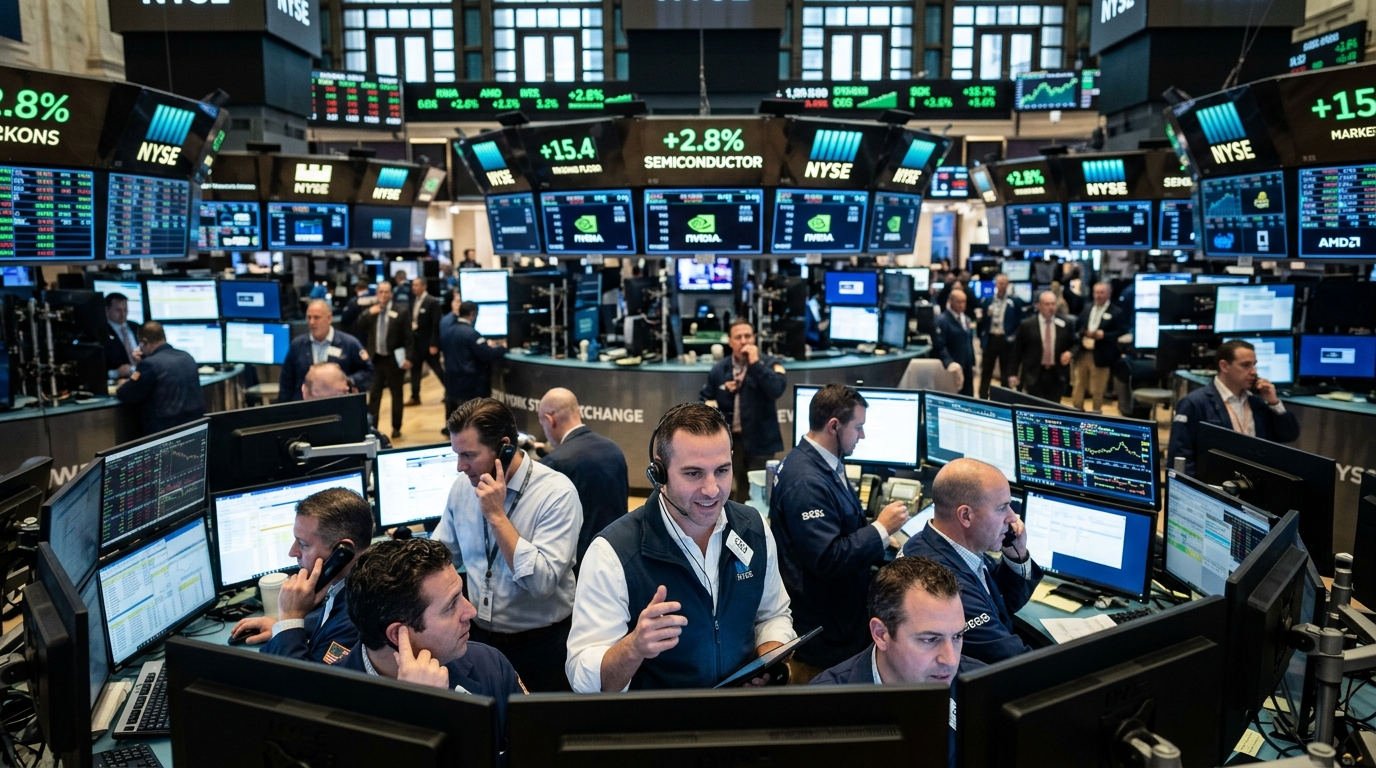
The market session of July 9, 2026, will be remembered by analysts as the day when 'AI fatigue' finally gave way to a new reality: the absolute dominance of semiconductor manufacturers in the global economic landscape. As Wall Street approached the closing bell, the excitement surrounding chip giants was not merely a speculative surge but a confirmation that the infrastructure of the next decade is being built on silicon.
The Strategic Importance of Semiconductors in 2026
According to analysis from Stephanie Guild, CIO of Robinhood Markets, retail investor behavior has fundamentally shifted. They are no longer searching for the next 'viral app' but are strategically positioning themselves with the providers of raw computing power. Semiconductors have transitioned from a cyclical commodity to a foundational necessity, akin to oil in the 20th century. The rise of stocks like NVIDIA, AMD, and Broadcom is driven not just by hardware sales, but by the fact that the AI software running on these systems has begun to generate tangible revenue for enterprises.
Goldman Sachs, through its senior leadership, notes that we are currently in the third wave of the AI investment boom. The first wave was about discovery, the second about building data centers, and now, in the summer of 2026, we are witnessing the wave of 'operational efficiency.' Companies that invested billions in chips over the past two years are now seeing margin improvements through automation, which in turn fuels new demand for even more powerful processors.
Consumer Confidence and the Retail Nexus
Dana Telsey, CEO of Telsey Advisory Group, provided a different perspective during Bloomberg's 'The Close.' Despite the pressure some retail sectors face due to persistent inflation, companies integrating cutting-edge technology are managing to maintain customer loyalty. The link between chipmaker performance and the consumer market is now direct: faster chips mean better personalized shopping experiences, more efficient supply chains, and ultimately, lower costs for the end consumer.
- Demand for specialized chips (ASICs) for edge computing is growing exponentially.
- Institutional investors are rotating capital from traditional software-as-a-service (SaaS) toward hardware manufacturers.
- Geopolitical stability in manufacturing hubs remains the primary tail-risk for the market.
Challenges and Outlook for H2 2026
Despite the euphoria, voices of caution warning against excessive valuations remain. The market appears to be pricing in a perfect execution of business plans by chipmakers, leaving little room for error. However, capital flows indicate that investors prefer the security of the 'real assets' of the digital age—semiconductor fabrication plants and chip architecture IP—over the uncertain business models of software startups.
"We are no longer just buying tech stocks; we are buying the building blocks of global GDP," a Goldman Sachs analyst remarked during the session.
In conclusion, Wall Street's close on July 9 confirms that semiconductors remain the engine of the global economy. Their ability to pull entire indices into positive territory, even amidst macroeconomic uncertainty, underscores their central role in the fourth industrial revolution. The question for the remainder of the year is not whether demand will persist, but whether supply can keep pace with the explosive needs of the global market.





