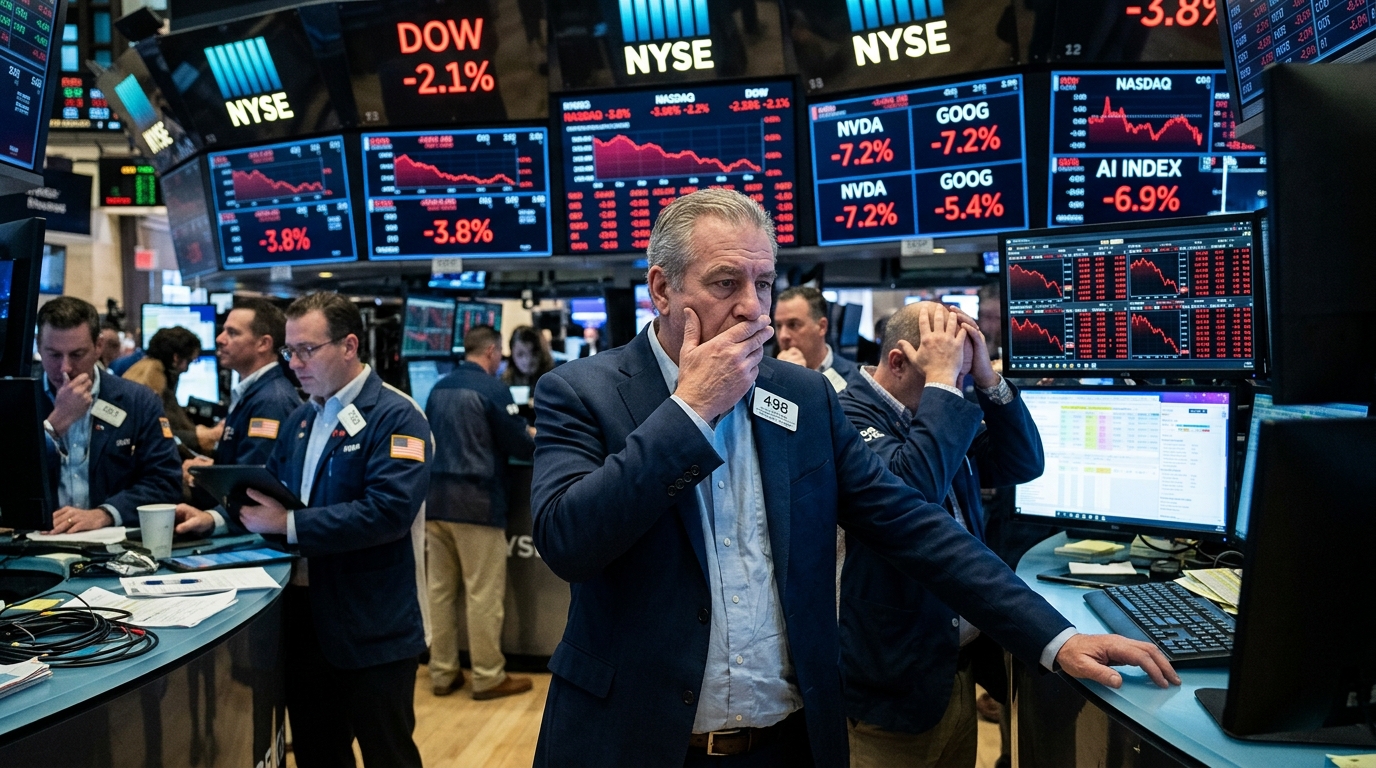
As of June 2026, the investment landscape surrounding Artificial Intelligence (AI) is reaching a critical inflection point. Following three years of nearly vertical growth, global stock markets in New York, London, and Tokyo are showing signs of exhaustion, with profit-taking dominating recent sessions. The era of "blank checks" for tech giants appears to be closing as institutional investors shift their focus from future promises to present-day balance sheets.
The Transition from Infrastructure to Implementation
For a long period, the market was fueled by the massive demand for infrastructure—primarily semiconductors and data centers. Companies like Nvidia and ASML saw their valuations soar to unprecedented heights. However, the current market pressure stems from a fundamental question: when will software companies and end-users begin to generate meaningful Return on Investment (ROI) from these tools? The sell-offs observed in recent weeks reflect analyst skepticism regarding whether the productivity gains offered by AI can justify the earnings multiples that have been priced in.
According to data from Wall Street, Capital Expenditure (Capex) among "Big Tech" continues to grow at rates exceeding 25% annually, yet revenue growth directly attributable to AI remains in the single digits for the majority of the corporate sector. This "credibility gap" is prompting fund managers to lock in profits, fearing a repeat of the dot-com bubble, albeit with different qualitative characteristics.
Macroeconomic Pressures and Geopolitical Uncertainty
The pressure on tech stocks is not solely due to internal industry factors. Central banks, despite expectations for aggressive rate cuts, are maintaining a cautious stance due to persistent inflation in the services sector. High interest rates disproportionately affect growth companies that rely on future cash flows, making the cost of capital for training new AI models prohibitive for smaller players.
- The rise of protectionism in the US and EU is impacting the semiconductor supply chain.
- New European Union regulations (AI Act) are imposing unforeseen compliance costs.
- Geopolitical tensions in Southeast Asia are causing concern over the stability of chip production.
Furthermore, the market is reacting to the growing energy crisis triggered by Large Language Models (LLMs). The need for massive amounts of electricity has made the energy sector an unexpected ally—and competitor—of technology, with investors now pivoting toward utilities that can support the "digital edifice."
Investor Sentiment and the Path Forward
Despite the current correction, many analysts view this as a "healthy decompression." Removing the speculative "froth" allows companies with real value and operating profits to stand out. The liquidations do not signal the end of AI, but rather its maturation as an investment category. Going forward, the market will reward not those who merely incorporate AI, but those who demonstrate they can reduce costs and increase profit margins through it.
"We are not facing a collapse, but a re-evaluation. The market is stopping to buy the narrative and starting to buy the results," says a leading strategist in London.
In conclusion, international markets are in a phase of seeking a new equilibrium. Artificial Intelligence remains the central pillar of the fourth industrial revolution, but the road to universal adoption and full profitability is proving to be more difficult and costly than initially estimated. Investors who survive this period of pressure will be those with the patience to look beyond quarterly volatility and the acumen to recognize companies that turn algorithms into real wealth.