

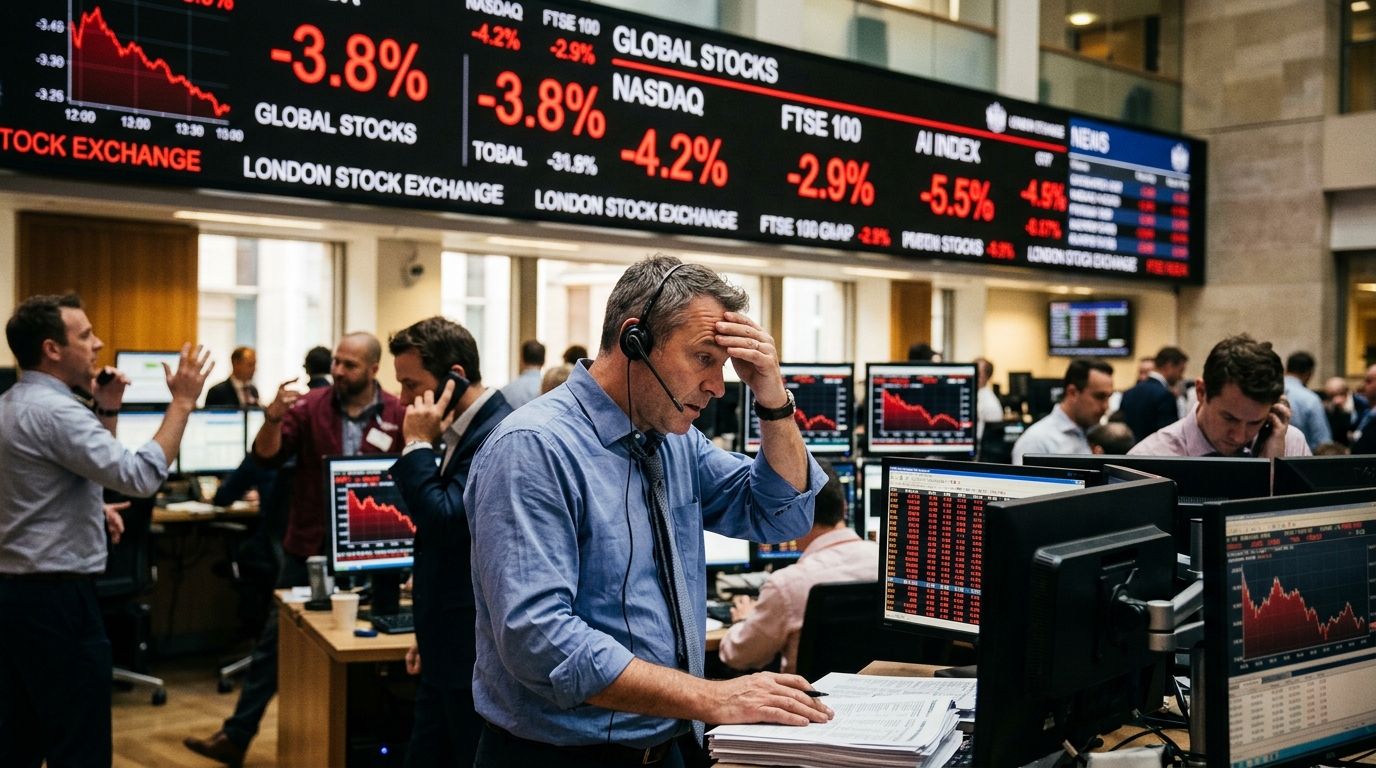
The era of "irrational exuberance" for Artificial Intelligence appears to be reaching a jarring conclusion. In recent weeks, global markets have experienced intense volatility, with Silicon Valley tech giants leading a downturn that many analysts describe as the long-awaited "correction" of the AI bubble. After two years of relentless growth, investors are beginning to ask the critical question: When will we see a return on the billions being poured into infrastructure?
The Moment of Truth for Big Tech
The recent earnings reports from bellwether companies like Microsoft, Alphabet, and Nvidia served as the catalyst for the current turmoil. While revenues remain high, capital expenditures (Capex) for developing data centers and purchasing specialized chips have skyrocketed to dizzying levels. The market is no longer satisfied with user growth or impressive model demos; it demands clear evidence that AI can generate profits that outweigh its massive operational costs.
- AI infrastructure spending is exceeding $100 billion annually for major players.
- Enterprise adoption of AI remains in the experimental stage, delaying the return on investment.
- Pressure on profit margins is becoming visible as energy and maintenance costs for LLMs rise.
According to analysts at Goldman Sachs, there is a risk that AI might turn out to be an "overly expensive solution for problems that haven't been fully defined yet." This sense of uncertainty has triggered a domino effect of liquidations, affecting not just the Nasdaq, but also the Nikkei in Japan and European indices, as investors rotate capital out of the tech sector in search of safer havens.
Bubble or Transition Period?
The question dominating trading floors is whether we are witnessing a repeat of the 2000 dot-com crash. There are similarities, such as the excessive concentration of capital in a few companies and astronomical valuations. However, the difference lies in the fact that today's AI protagonists are already profitable entities with massive cash reserves, unlike the "ghost companies" of the late 90s.
"We are not seeing the end of AI, but the end of free credit and blind faith. The market is maturing and demanding results," says a leading economist from the City of London.
The stock retreat also reflects broader macroeconomic concerns. With interest rates remaining higher for longer than expected, the cost of borrowing to develop cutting-edge technologies is becoming burdensome. Artificial Intelligence is no longer immune to monetary policy shifts.
Global Economic Implications
The slump in tech stocks has a direct impact on global supply chains. A potential slowdown in semiconductor demand could hit economies like Taiwan and South Korea hard. In Europe, the impact is more indirect but equally significant, as US volatility inevitably dampens investor sentiment across European exchanges.
For the global economy, this retreat serves as a wake-up call. The "AI-first" strategy must be accompanied by sustainable business models rather than just riding the hype wave. The need for specialized talent and energy sufficiency remains paramount, but funding will now be much more selective and scrutinized.
Conclusion: The Road Ahead
The receding AI mania is, ultimately, a healthy development for the global financial system. It allows for the removal of speculative elements and focuses attention on applications that offer real-world value. The technology will continue to evolve, but the road to universal adoption will be longer and more arduous than Wall Street's optimists predicted. The "gold rush" phase of AI is over; the era of hard work and proven utility has begun.





