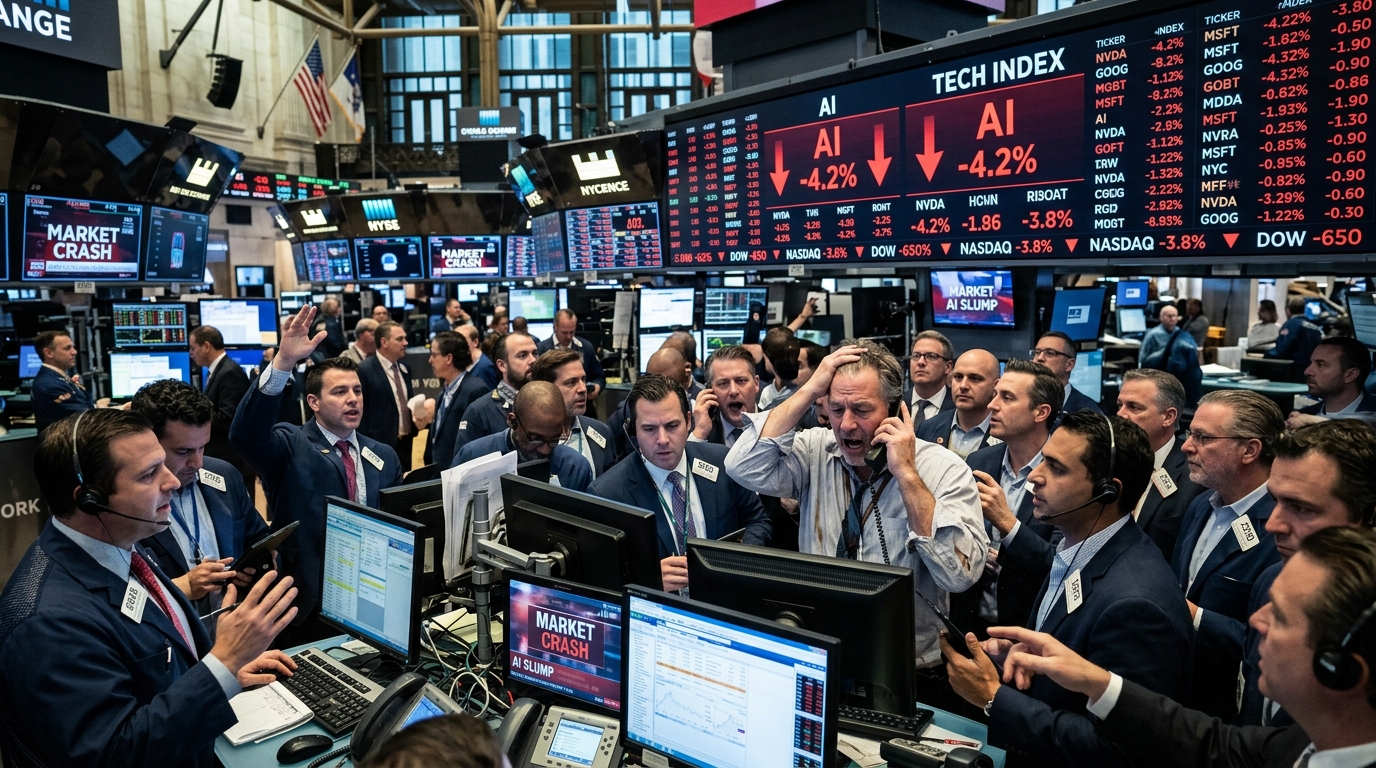
July 8, 2026, will likely be remembered as the day the 'promise' of Artificial Intelligence collided with the unforgiving reality of balance sheets. Following three years of nearly delirious growth, global technology stocks are undergoing a violent correction, dragging down indices from Wall Street to Tokyo and London. The catalyst was not a single failure, but a cumulative realization: the infrastructure costs for AI are colossal, while the revenues from its implementation remain, for the majority of companies, disproportionately small.
The Tyranny of Returns and the End of the Grace Period
For more than two years, investors rewarded any company that added the 'AI' suffix to its announcements. Nvidia, Microsoft, and Alphabet saw their market capitalizations soar to dizzying heights, based on the expectation that Generative AI would radically transform global productivity. However, second-quarter 2026 results show a different picture. Capital expenditures (CAPEX) for purchasing processors and building massive data centers have reached levels that threaten the liquidity of even the strongest players.
According to analysts at Goldman Sachs and Morgan Stanley, the market has begun to realize that enterprise adoption of AI is lagging. Companies are hesitant to fully integrate Large Language Models (LLMs) due to data security concerns, model hallucinations, and the high cost of subscriptions. This 'adoption gap' has created a hole in shareholder expectations, leading to what many are now calling 'the bursting of the AI bubble.'
The Energy Wall and Geopolitical Pressures
Another factor fueling the decline is energy costs. Running AI models requires vast amounts of electricity at a time when global grids are under pressure from the green transition. The recent surge in energy prices in Europe and power supply constraints in US tech hubs, such as Virginia, have made it clear that scaling AI is not just a software issue, but one of physical resources.
"The market is realizing that AI is not magic, but a capital-intensive and energy-intensive industry. The period of free growth is over," says a leading strategic analyst in the City of London.
Meanwhile, geopolitical tensions surrounding the semiconductor supply chain remain at a fever pitch. New export restrictions on advanced chips to Asia have hit hardware manufacturers' revenues, creating a risk-averse climate. Investors are now moving away from high tech, seeking refuge in more traditional sectors such as utilities and consumer staples.
From Hype to Substance: A Healthy Correction?
Despite the panic of the day, many industry experts argue that this retreat is necessary for the long-term health of the sector. As happened with the dot-com bubble in 2000, the current crisis will clear the landscape, removing companies without a sustainable business model and making room for those that offer real value.
- Software companies will be forced to prove the value of their AI tools through actual customer profits.
- The focus will shift from "larger models" to "more efficient models" (small language models), which require fewer resources.
- Regulatory intervention, such as the full implementation of the AI Act in Europe, will provide a more stable, albeit stricter, operating framework.
In conclusion, the stock market crash does not mean the end of Artificial Intelligence. On the contrary, it marks the transition from the adolescence to the adulthood of the technology. The challenge for the coming months will be managing volatility as the market tries to find a new balance between excitement for the future and the financial discipline of the present.