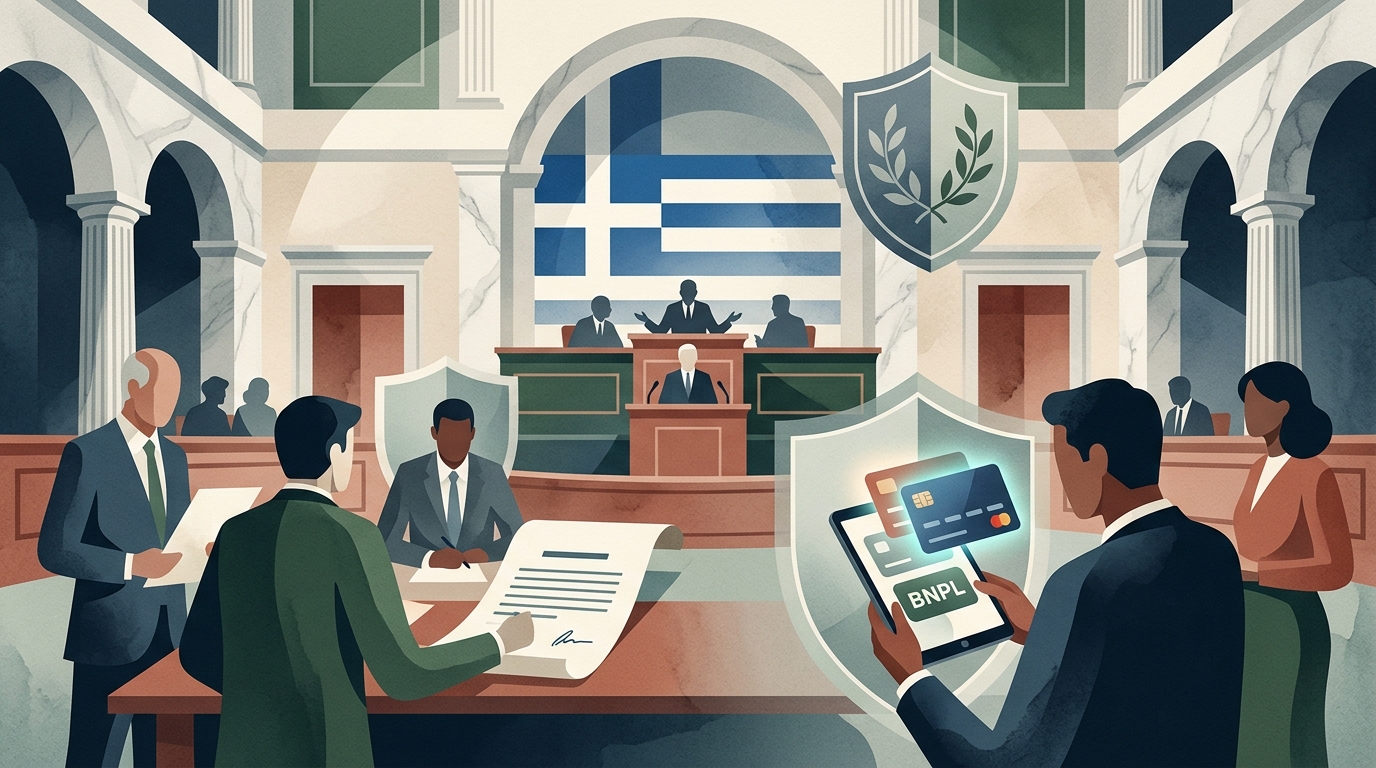
In an era where inflation and the cost of living are testing household resilience, the Greek government is undertaking a bold regulatory intervention in the consumer credit market. Minister of Development Takis Theodorikakos presented a new consumer protection bill to Parliament, aiming to establish the most robust and protective framework within the European Union. This move is not merely a transposition of EU directives (CCD II), but a deliberate choice to exceed minimum requirements to curb over-indebtedness.
The APRC Cap: Ending 'Predatory' Charges
The heart of the new legislation lies in the restriction of the Total Annual Percentage Rate of Charge (APRC). For the first time, a maximum limit is being set on the total cost of consumer loans, including interest, commissions, and any other charges. This regulation directly targets products that previously 'trapped' consumers with low nominal interest rates but exorbitant hidden costs.
According to Mr. Theodorikakos, this cap will be calculated based on a fixed margin above the current European Central Bank rates, ensuring that consumer credit remains a tool for growth rather than a mechanism for citizen bankruptcy. This intervention comes at a time when credit card interest rates in Greece remain among the highest in the Eurozone, creating a sense of inequity among borrowers.
Regulating 'Buy Now Pay Later' (BNPL) and Digital Credit
One of the most innovative and necessary aspects of the reform is the inclusion of 'Buy Now Pay Later' (BNPL) services within the strict supervisory framework. Until now, many of these services operated in a 'gray zone,' offering seemingly interest-free installments without the checks applicable to traditional banks. The new framework mandates:
- Compulsory creditworthiness assessment of the customer, even for small amounts.
- Transparency in contract terms using simple and understandable language.
- A 14-day right of withdrawal, as is the case with traditional loans.
This move is considered essential as the rapid rise of fintech companies has transformed the retail landscape. Many young consumers have been led into debt spirals without realizing that multiple small BNPL installments collectively exceeded their disposable income.
Stricter Controls and the 'End' of Irresponsible Lending
The bill introduces the concept of 'responsible lending.' Credit providers will now be held accountable if they grant a loan to a consumer whose financial situation does not allow for repayment. Creditworthiness checks will no longer be a formality but a substantive assessment of the borrower's income, expenses, and existing obligations.
"We do not want an economy based on debt bubbles, but a market where the consumer feels safe and borrowing is productive," the Minister emphasized during his presentation.
Furthermore, the bill strengthens the powers of the General Secretariat of Commerce to conduct audits and impose fines. Penalties for companies violating the new rules will be exceptionally severe, acting as a deterrent against misleading or exploitative practices.
Social and Economic Implications
Criticism from financial institutions focuses on the risk of liquidity constraints. It is argued that excessive restrictions may lead to the exclusion of segments of the population from accessing legal credit, potentially driving them toward informal and dangerous sources of finance. However, the government counters that the long-term stability of the economy depends on avoiding a new wave of 'red' (non-performing) loans, especially in consumer credit, which is more vulnerable to fluctuations.
At the European level, Greece is pioneering by adopting provisions that other countries are still processing. The success of the venture will be judged in practice: by the speed of implementation of controls and whether banks and fintech companies adapt smoothly to the new reality without 'freezing' the market.