The meteoric rise of Artificial Intelligence (AI) has transcended the realm of technological novelty to become an existential challenge for the global financial architecture. According to recent warnings from senior officials at the European Central Bank (ECB) and various regulatory bodies, the velocity of AI integration within banking processes is outstripping the capacity of regulators to oversee it, creating a perilous security vacuum.
The 'Black Box' Problem and the Mandate for Transparency
A primary point of contention between the banking establishment and the tech sector is the lack of interpretability in modern algorithms. In traditional banking, every decision—from mortgage approvals to high-stakes investment risk assessments—must be justified and traceable. However, Generative AI often functions as a 'black box,' where outcomes emerge from billions of parameters that even their creators struggle to decode fully.
Regulators warn that if banks rely on such models for critical decision-making, the principle of accountability vanishes. "We cannot allow an algorithm to dictate financial stability without possessing the 'key' to its logic," a senior official from the ECB's Supervisory Board noted. The concern is compounded by the fact that training data may harbor latent biases, leading to systemic discrimination that remains invisible to traditional auditing methods.
Systemic Risk and the Specter of the 'Flash Crash'
Beyond transparency, the paramount fear for regulators is systemic risk. The widespread adoption of identical, dominant AI models by multiple financial institutions simultaneously could trigger 'herd behavior' in the markets. If multiple algorithms react identically to a specific economic signal—for instance, by initiating massive sell-offs—the consequences could be catastrophic, precipitating a flash crash that no human intervention could halt in time.
- Homogenization of Risk: When diverse institutions utilize the same underlying models (e.g., from OpenAI or Google), the model's flaws become the system's flaws.
- Cybersecurity Threats: AI provides cybercriminals with sophisticated tools to breach banking systems through advanced phishing or automated vulnerability discovery.
- Third-party Dependency: Banks are increasingly reliant on a handful of cloud and AI providers, creating a new form of monopolistic dependency.
"Artificial Intelligence is a power multiplier. In the hands of a bank, it can deliver efficiency; in the heat of a crisis, it can deliver chaos," warns a report from the European Banking Authority (EBA).
The Regulatory Gap and the AI Act
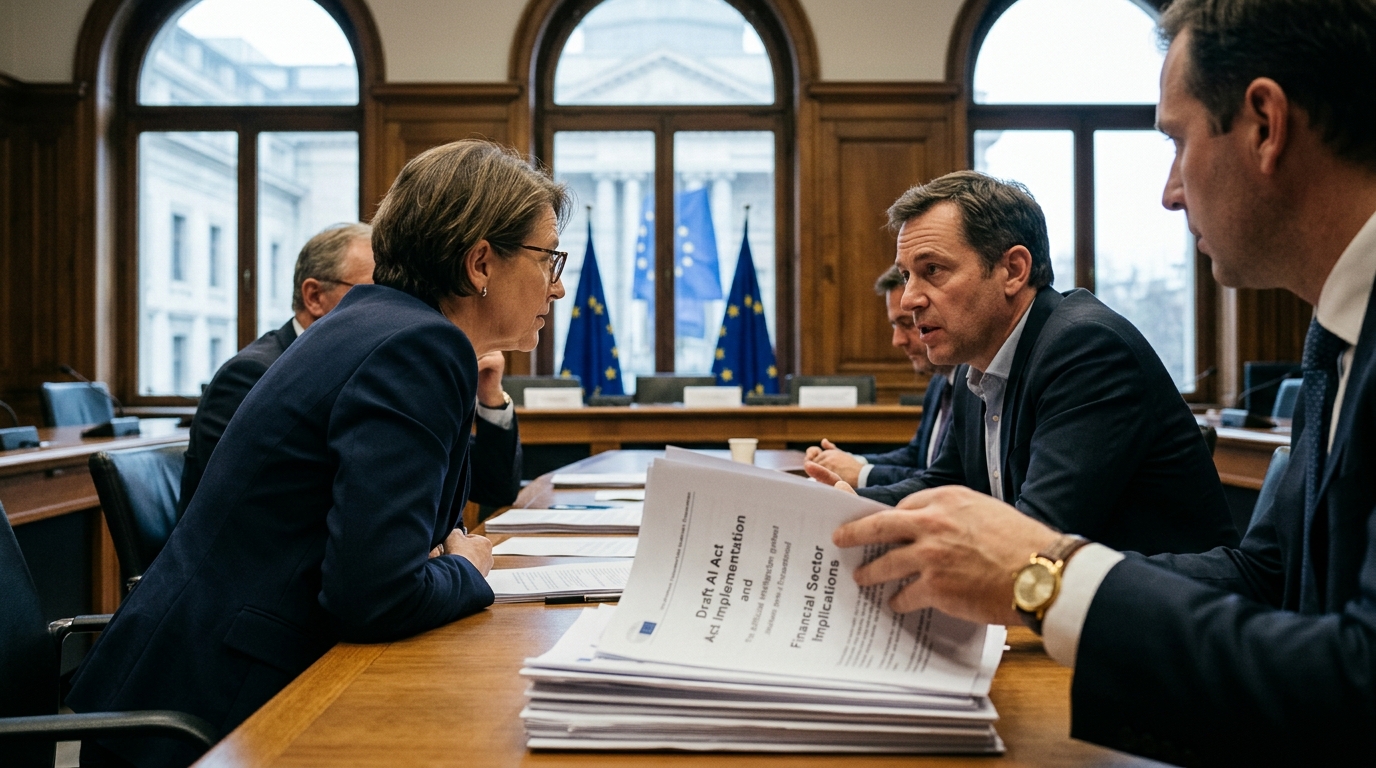
While the European Union led the world with the passage of the AI Act, bankers argue that the legislation is already trailing the curve. The speed at which new models (such as GPT-5 or specialized financial LLMs) emerge renders static rules obsolete. Regulators are now being urged to shift from 'checklist-based compliance' to 'dynamic supervision.'
This shift implies that banks must continuously demonstrate the safety of their models, subjecting them to stress tests that are not only financial but algorithmic. The challenge is immense: how do you regulate a system that learns and evolves every second? Europe stands at a crossroads, attempting to protect consumers without stifling the innovation necessary for European banks to compete with the titans of Wall Street and Silicon Valley.
The Geopolitical Dimension
Finally, the geopolitical aspect cannot be ignored. The majority of AI models currently in use are developed outside the EU. This creates a strategic dependency that alarms Brussels. If access to these models were restricted or if providers altered their terms of service, the European banking infrastructure could find itself vulnerable. The push for 'sovereign European AI' in the financial sector is no longer just a technological goal; it is a matter of national and economic security.