The landscape of Greek banking in the summer of 2026 bears no resemblance to the fragile state of the previous decade. Following a prolonged period of restructuring, domestic credit institutions have entered a phase of mature growth, achieving performances that, in certain metrics, surpass European averages. Convergence is no longer a distant goal but a reality reflected in the first-half balance sheets of the year.
Profitability as a Growth Driver
The first five months of 2026 confirmed analysts' expectations. Greek banks recorded robust net profits, fueled by high interest margins and effective cost management. Despite the gradual de-escalation of interest rates by the European Central Bank, Net Interest Income (NII) remained resilient, thanks to the structure of the loan portfolios and the containment of deposit costs.
One of the primary areas where Greek banks outperform their European peers is the Return on Tangible Equity (RoTE). While the European average hovers around 12-13%, major Greek banks are achieving rates exceeding 15%, making them highly attractive to international institutional investors. The successful completion of the Hellenic Financial Stability Fund (HFSF) divestment marked a full return to the private sector, bolstering market confidence.
Digital Transformation and Operational Efficiency
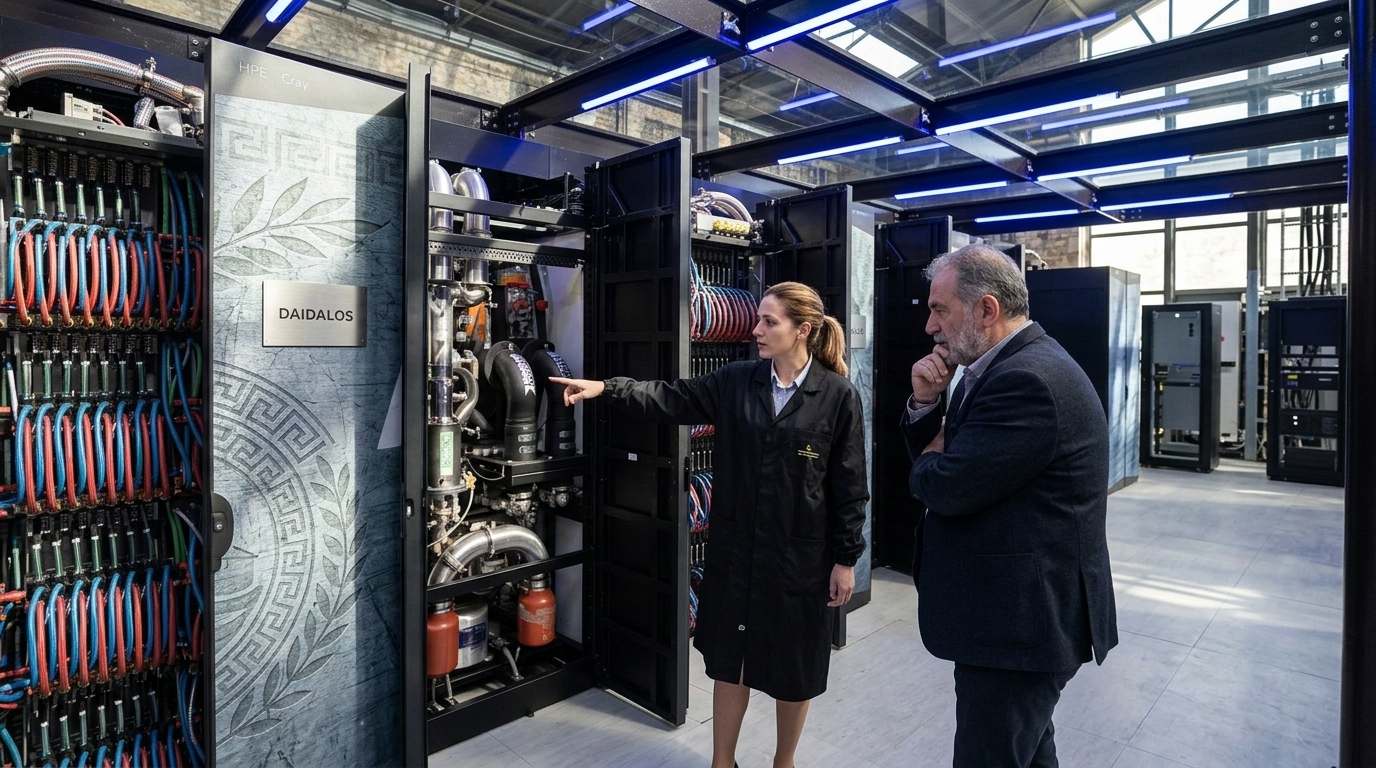
If there is one area where Greece has 'leapfrogged' traditional European markets, it is digital banking. Greek banks, benefiting from not being as burdened by legacy systems as some Central European giants, invested heavily in Artificial Intelligence and cloud computing.
- Over 95% of transactions are now conducted digitally.
- The use of AI for product personalization has reduced operating costs by 20%.
- Greek banking digital platforms are considered among the most user-friendly in the EU.
This technological superiority translates into one of the lowest cost-to-income ratios in Europe. Greek banks operate with leaner structures, having adjusted their branch networks and personnel to the needs of the new era without sacrificing service quality.
Challenges and the Social Footprint
However, this success does not come without criticism. The significant spread between lending and deposit rates remains a thorny issue for Greek society. While banks are fortifying their capital, borrowers are pressured by the cost of money, a fact that has sparked political debates regarding the need for a fairer distribution of profits.
"The stability of the banking system is the backbone of the economy, but citizen trust is earned when the prosperity of numbers translates into easier access to housing and entrepreneurship," government sources note.
The management of Non-Performing Exposures (NPEs) continues through the "Hercules" program, with ratios now approaching the levels of their European counterparts. The challenge for the remainder of 2026 will be channeling liquidity into the real economy, particularly toward small and medium-sized enterprises (SMEs) that form the core of the Greek market, as well as financing green transition projects.
Conclusion
Greek banks have transformed from the "weak link" of the Eurozone into models of resilience and profitability. Convergence with Europe has been achieved in terms of regulatory indices, but the true test will be maintaining these performances in a lower interest rate environment and strengthening their social role in the Greece of tomorrow.