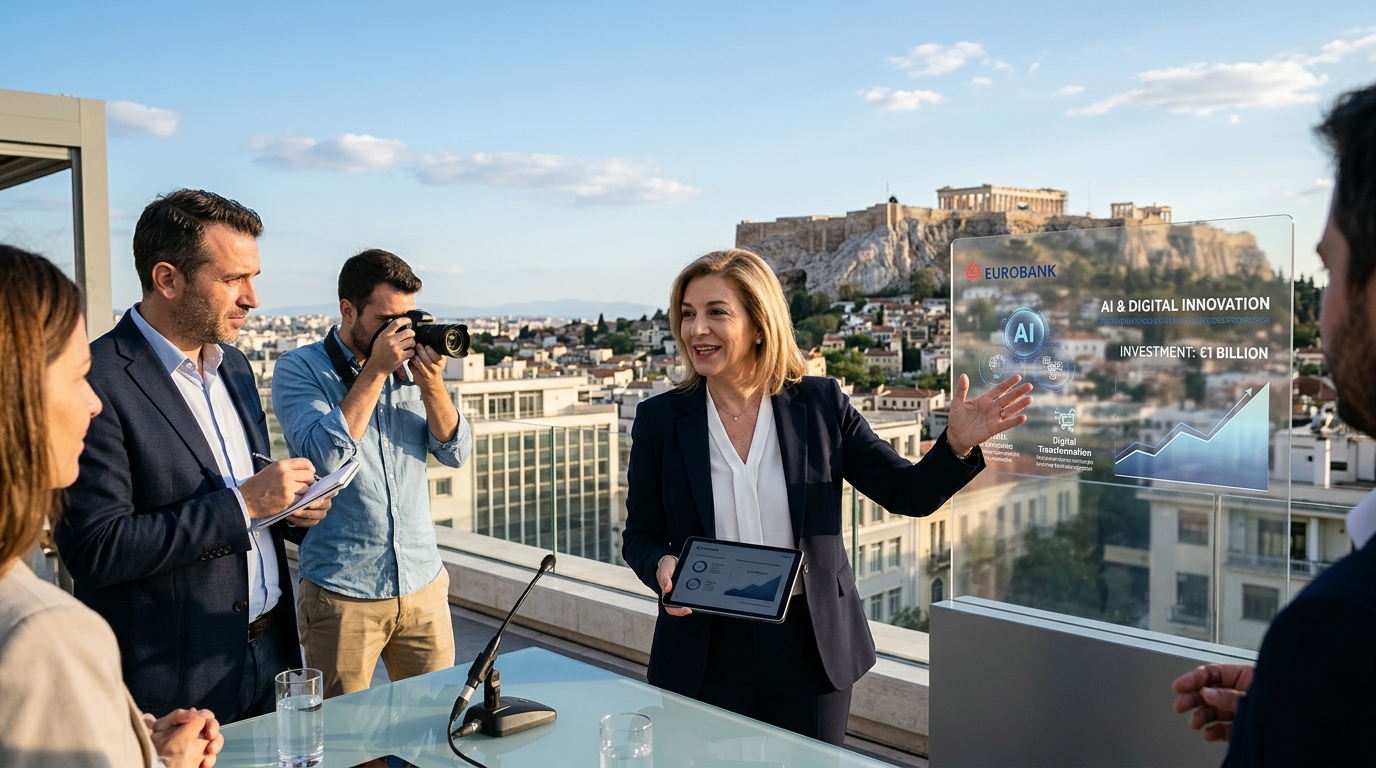
The Greek banking landscape is at the threshold of a new era, decisively moving past the introversion of previous years. Eurobank's announcement of a €1 billion investment program over the next three years is not merely a business move; it is a statement of intent to dominate the digital transformation of Southeast Europe. With Artificial Intelligence (AI) and advanced Cloud technologies as its core pillars, the bank aims to redefine its relationship with customers, making it more personal, immediate, and efficient.
The Digital Pillar: AI and Cloud at the Core
This investment is not just about upgrading existing systems; it is about creating a new ecosystem. Eurobank aims to leverage Generative AI to automate internal processes and provide personalized advice to its clients. Imagine a digital assistant that doesn't just answer standardized questions but analyzes a user's financial profile in real-time, suggesting investment products or savings methods with a precision that previously required hours of work from specialized personnel.
The transition to the Cloud is the foundation of this effort. By storing and processing data in scalable infrastructures, the bank gains the necessary agility to launch new products in weeks rather than months. Simultaneously, transaction security is enhanced through machine learning algorithms that can detect suspicious movements and fraud attempts before they are even completed, protecting depositors' capital with unprecedented efficiency.
The "Phygital" Strategy and Customer Experience
Despite the massive investment in technology, Eurobank's management, led by CEO Fokion Karavias, insists on the "Phygital" model—a combination of physical presence and digital capabilities. The €1 billion will also be directed toward restructuring branches, which are being transformed from transaction processing centers into high-value-added advisory hubs.
- Personalization: Using AI to predict customer needs before they are even expressed.
- Speed: Approval of loans and credit limits in seconds through automated risk assessment systems.
- Accessibility: Enhancing m-Banking with voice command capabilities and biometric identification.
This approach aims to attract the new generation of customers (Gen Z and Millennials), who demand banking services that operate with the ease of a social media app. At the same time, the bank is investing in staff training so they can manage these new tools, ensuring that technology acts as an assistant and not a substitute for human judgment.
Economic Implications and Competition
Eurobank's move comes at a time when competition from so-called "Neo-banks" and Fintech companies is intensifying globally. By investing such a significant amount, the bank fortifies its position not only in Greece but also in the markets of Cyprus and Bulgaria, where it maintains a strong presence. The reduction in operating costs through automation is expected to significantly improve the cost-to-income ratio, allowing the bank to offer more competitive interest rates and lower fees in the medium term.
"Technology is no longer a supporting tool; it is the heart of our banking strategy for the next decade," sources close to the management state.
In conclusion, Eurobank's investment program serves as a roadmap for how a traditional bank can transform into a technological powerhouse. The success of this venture will be judged by the speed of implementation and the bank's ability to convince its customers that the digital transition does not mean impersonal service, but an upgraded, safer, and fairer banking experience.