

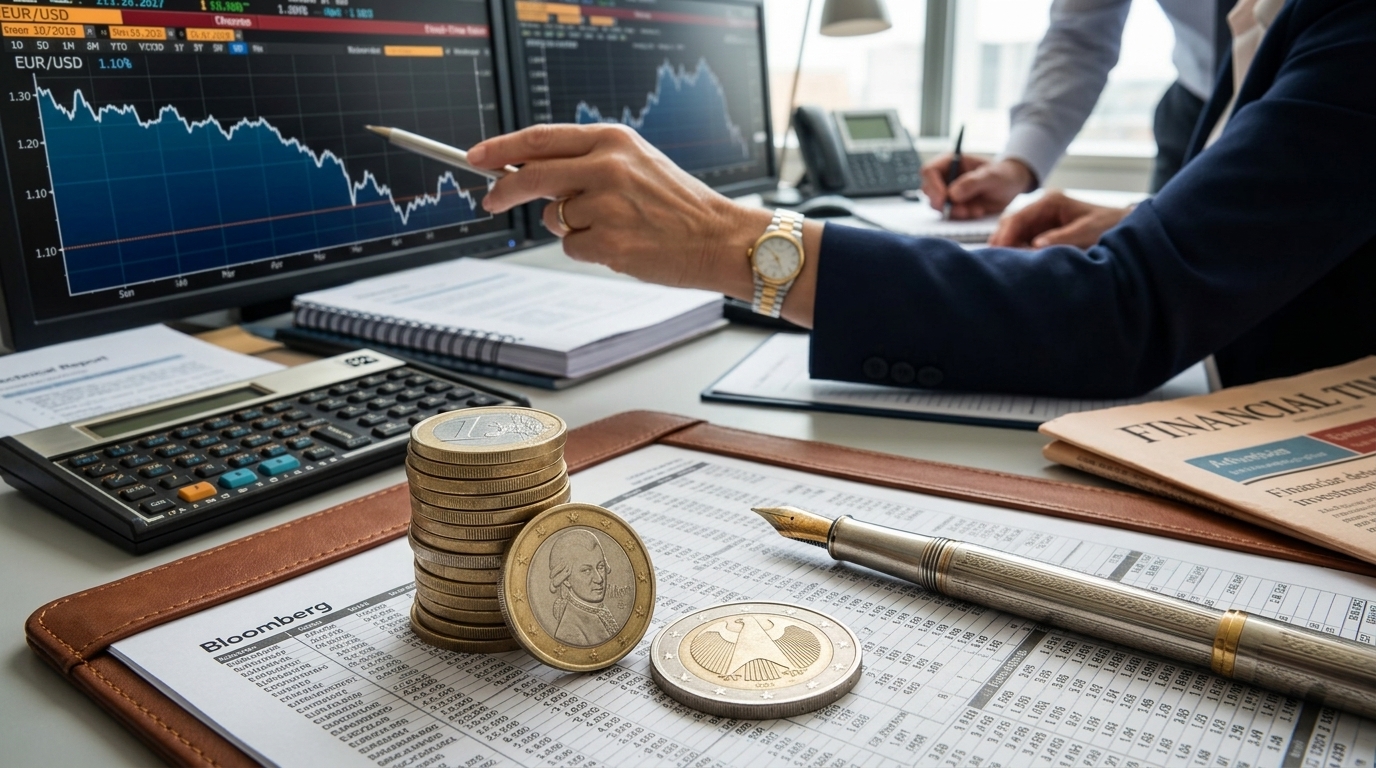
The euro's luster in international currency markets appears to be fading dangerously. While the common European currency enjoyed a period of relative stability and growth in previous months, the sentiment on Wall Street has shifted dramatically. Major investment houses, from Goldman Sachs to JPMorgan, are revising their forecasts downward, with many analysts now seeing the $1.10 level against the dollar not as a floor, but as a waypoint in a longer downward trajectory.
American Exceptionalism and the Growth Gap
The primary reason for this Wall Street pivot is the divergence in growth rates between the two sides of the Atlantic. The US economy continues to demonstrate remarkable resilience, fueled by strong domestic consumption and dominance in the technology and artificial intelligence sectors. Conversely, the Eurozone remains trapped in a cycle of low growth, with the continent's engine, Germany, struggling with a structural crisis in its heavy industry model.
Investors observe that the United States manages to maintain high interest rates without triggering a deep recession, making the dollar extremely attractive for those seeking yield. In Europe, the European Central Bank (ECB) finds itself in a much more difficult position: it must balance the need for rate cuts to stimulate the economy against the risk of letting inflation reignite due to currency depreciation, which makes energy imports more expensive.
Political Uncertainty and the Fear of Populism
Beyond purely economic metrics, Wall Street is deeply concerned about the political landscape in Europe. Recent elections and the rise of Euroskeptic forces in key countries like France have created a cloud of uncertainty. The lack of a unified fiscal policy and the difficulty of decision-making in Brussels make the euro vulnerable to speculative pressure.
- Political paralysis in France hinders necessary structural reforms.
- The German coalition government faces internal friction preventing strategic investment.
- A lack of progress on the Capital Markets Union discourages foreign investors.
"The euro is not just a currency; it is a political project. When political unity falters, the currency inevitably follows," notes a senior investment banking executive in New York.
Monetary Policy and the Carry Trade
Another factor weighing on the euro is the 'carry trade' strategy. With the Federal Reserve maintaining interest rates at higher levels for longer compared to the ECB, investors borrow in euros (at a lower cost) to invest in dollars or other high-yield currencies. This outflow of capital from the Eurozone creates constant selling pressure on the euro.
Furthermore, Wall Street is pricing in that the ECB will be forced into more aggressive rate cuts within 2026 to prevent prolonged stagnation. Every time markets expect a rate cut in Europe without a corresponding move in the US, the euro loses ground. Market psychology has solidified: the dollar is seen as the 'safe haven' and the currency of growth, while the euro is treated as a low-yield, high-risk asset.
Conclusion: Toward a New Equilibrium?
The slide toward 1.10 may only be the beginning. If Europe fails to present a convincing plan for restoring productivity and deepening integration, the euro will continue to lose its significance as a global reserve currency. Wall Street is not 'punishing' the euro out of malice; it is responding to the hard data of a continent that is aging demographically and lagging technologically. For now, the dollar remains the undisputed king, and the euro must prove its relevance in a world that does not wait for laggards.





