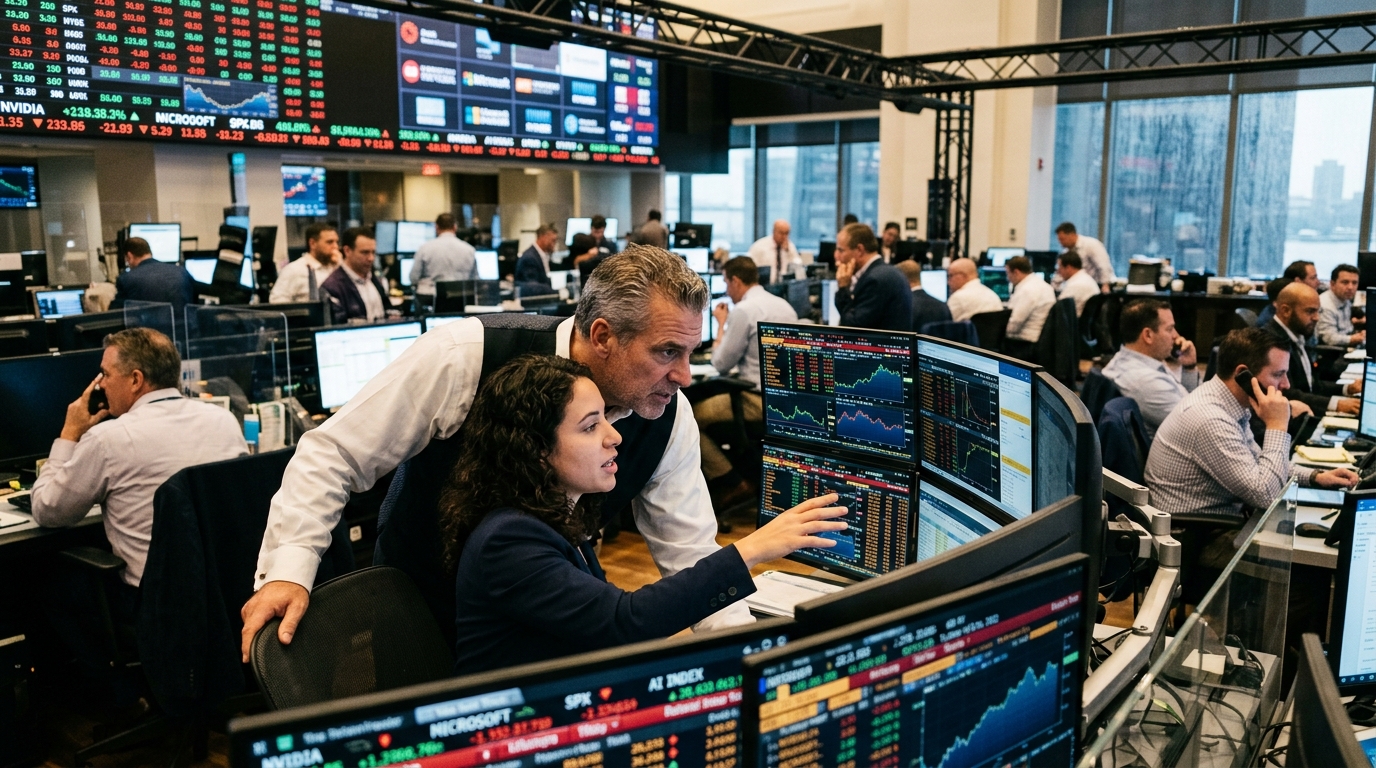
Wall Street is navigating a period of profound existential crisis, trapped between the thrill of a "once-in-a-generation" technological revolution and the cold dread that the dot-com bubble's history might be repeating itself. As we move through June 2026, the Artificial Intelligence (AI) narrative is no longer a simple case of future growth; it has become a rigorous accounting audit of capital expenditures (CapEx) versus actual revenue.
The Era of Hyper-Investment
The so-called "Hyperscalers"—Microsoft, Alphabet, Meta, and Amazon—have committed hundreds of billions of dollars to building data centers and purchasing Nvidia processors. The question looming over the New York Stock Exchange is simple yet relentless: When will we see the return on investment (ROI)?
Until recently, the market rewarded any announcement containing the word "AI." However, recent quarterly reports indicate a shift in investor sentiment. While spending is growing at rates of 30-40% annually, revenue from AI services, such as Copilot or next-generation advertising algorithms, is growing at a much slower pace. This disparity has caused nervousness, with analysts from Goldman Sachs and Barclays warning that "market patience is not inexhaustible."
Nvidia as the Sole Winner (For Now)
At the center of this storm lies Nvidia. The company has become the barometer for the entire global economy. As long as Nvidia reports earnings that exceed expectations, the AI narrative remains viable. However, many analysts point to a risk: Nvidia is selling the "picks and shovels" to a gold miner who hasn't found the motherlode yet. If Nvidia's customers—the large cloud providers—decide to slow down their spending because their own customers aren't buying enough AI services, then the entire structure is at risk of collapse.
- AI capital expenditures are expected to exceed $200 billion by the end of 2026.
- AI penetration in enterprises remains in the experimental stage for 70% of Fortune 500 companies.
- Energy costs for operating LLMs (Large Language Models) are becoming a significant hurdle to profitability.
The Comparison to 1999
Wall Street bears see haunting similarities to the late 1990s. Back then, telecommunications companies spent billions laying fiber optic cables, believing internet demand would be immediate. The demand did come, but ten years later, and most of the companies that built the infrastructure went bankrupt. Today, the fear is that we are building an AI infrastructure far larger than what the current economy can absorb.
"Artificial intelligence is the future, but the future doesn't always arrive at the pace required by Wall Street's quarterly earnings," notes a senior analyst at Morgan Stanley.
On the other hand, optimists argue that AI is not just a new application but a new mode of production. The productivity gains promised by AI—from automated coding to drug discovery—could add trillions to global GDP. For them, current volatility is merely the noise before the big growth explosion.
The Energy and Regulatory Wall
Beyond the numbers, two other factors complicate Wall Street's decision-making. The first is energy. AI data centers consume vast amounts of electricity, straining power grids and driving up costs. The second is regulation. With the European Union implementing the AI Act and the US considering antitrust investigations against Microsoft and Nvidia, political risk is higher than ever.
In conclusion, Wall Street is in a "wait and see" mode. The next phase of the market will not be judged by how many chips Nvidia can manufacture, but by whether businesses and consumers are willing to pay for artificial intelligence. Until then, volatility will be the investors' only certain ally.