

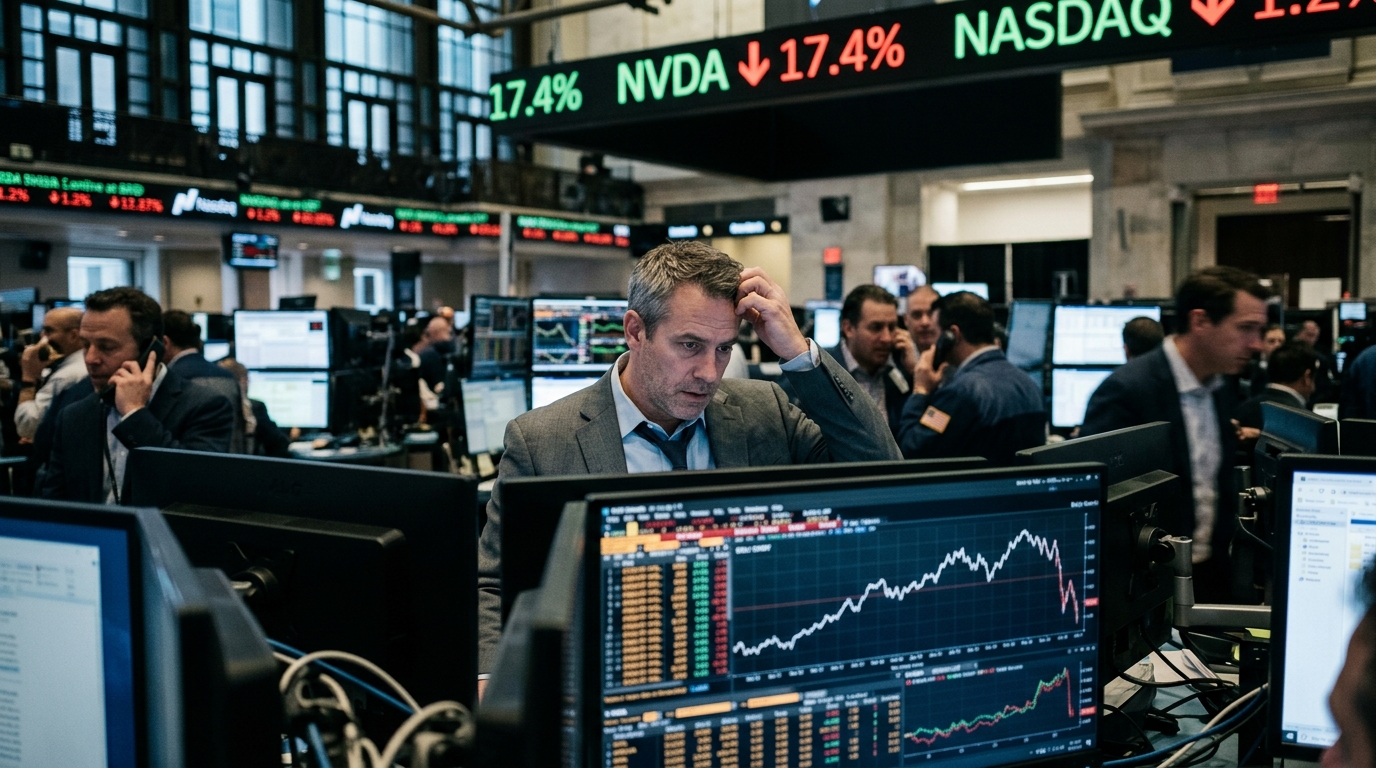
The technology market is navigating one of the most pivotal stretches in recent financial history. Nvidia, the semiconductor giant that has become the de facto face of the Artificial Intelligence (AI) revolution, recently saw its stock price retreat by 17% from its all-time high. To some, this dip represents the long-awaited popping of an overextended bubble; to others, it is a healthy correction in a secular bull market that will define the 21st century. As of July 8, 2026, the central question for Wall Street and Main Street alike is clear: Is Nvidia finally cheap, or are the fundamental pillars of its valuation beginning to crumble?
The Anatomy of a Correction: Why Is the Leader Sliding?
Nvidia’s 17% decline did not occur in a vacuum. Several macroeconomic and company-specific factors have converged to dampen investor enthusiasm. Primarily, profit-taking has become the order of the day. After a historic run that saw the company’s market capitalization rivaling global superpowers, institutional investors are rebalancing portfolios and locking in gains. Secondly, concerns regarding the capital expenditure (CAPEX) cycles of Nvidia’s largest customers—the so-called hyperscalers like Microsoft, Meta, and Alphabet—are mounting. Markets are increasingly skeptical about how quickly the billions spent on Blackwell and H200 chips will translate into tangible bottom-line growth from AI-driven services.
Furthermore, geopolitical risks remain a persistent overhang. Export restrictions to China and the high concentration of manufacturing at TSMC’s facilities in Taiwan create a fragile supply chain. While demand remains at record levels, the geopolitical chessboard is subject to shifts that no amount of engineering prowess can fully mitigate. Investors are beginning to price in a 'risk premium' for these external variables.
The Blackwell Cycle and Competitive Moats
Despite the stock’s recent volatility, Nvidia’s technological moat remains formidable. The Blackwell architecture, promising massive leaps in computational throughput while significantly reducing power consumption, is the industry benchmark for generative AI. CEO Jensen Huang has masterfully transitioned Nvidia from a hardware vendor to a full-stack AI ecosystem provider. The company’s CUDA software platform remains its most potent weapon, effectively locking developers into the Nvidia environment and making it prohibitively expensive and complex to switch to rival offerings from AMD or Intel.
However, the competitive landscape is shifting. Big Tech firms are no longer content to be mere customers; Apple, Google, and Amazon are aggressively developing their own custom silicon (ASICs) to optimize specific AI workloads. While these internal chips may not match the raw versatility of Nvidia’s GPUs across all applications, they offer superior efficiency for inference and specific training tasks, potentially eroding Nvidia’s market share in the long run.
Valuation Metrics: Is This a Bargain or a Trap?
From a purely statistical standpoint, Nvidia’s valuation has become more palatable. The Forward P/E (Price-to-Earnings) ratio, while still elevated compared to the broader S&P 500, has compressed significantly due to the company’s staggering earnings growth. The debate over whether the stock is 'cheap' hinges entirely on one's outlook for AI adoption. If AI is indeed the 'Fourth Industrial Revolution,' the current valuation might be seen as a rare entry point. Conversely, if we are witnessing a period of irrational exuberance reminiscent of the 1990s dot-com era, a 17% drop could be just the beginning of a deeper reset.
Wall Street analysts remain divided. Bulls argue that Nvidia is not just selling chips but the very infrastructure of the future, citing the massive backlog for Blackwell systems. Bears, however, warn that expectations have reached such dizzying heights that even a minor 'beat and raise' quarter might not be enough to satisfy the market’s thirst for growth. The reality likely lies in the middle: Nvidia is a generational company trading at a premium price, but one that is now slightly more grounded in reality.
Conclusion: A Strategy of Patience or Action?
For the long-term investor, volatility is the price of admission to innovation. Nvidia has demonstrated an uncanny ability to reinvent itself—from gaming to cryptocurrency mining and now to the backbone of global AI. A 17% pullback offers a necessary breather in a rally that was beginning to look unsustainable. Whether the stock is truly 'cheap' will not be decided by technical charts, but by the global economy’s ability to monetize AI effectively. Until that ROI becomes clear, Nvidia will continue to serve as the ultimate barometer of technological sentiment.





