

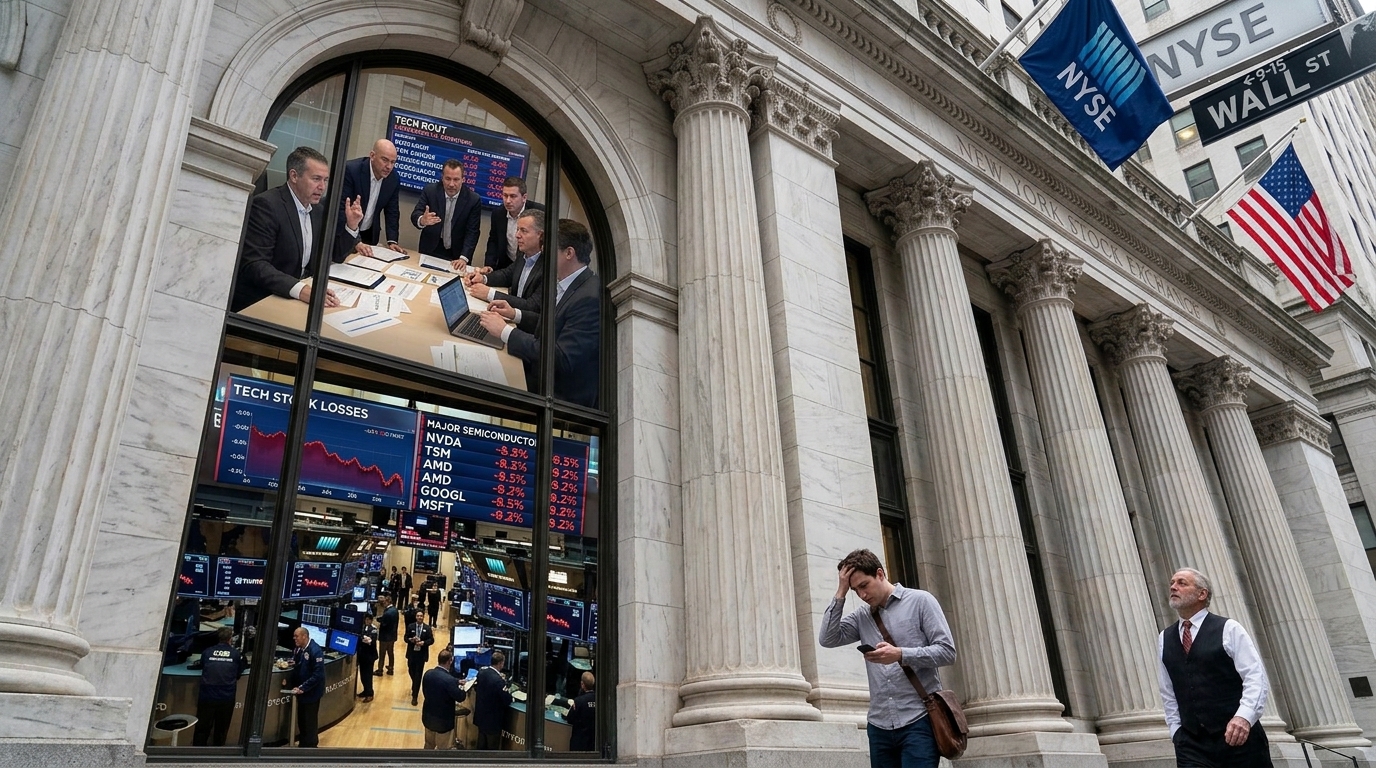
Tuesday, June 23, 2026, marks a pivotal moment in the financial markets as the long-standing AI-driven rally faces its most significant challenge yet. The S&P 500 and the Nasdaq Composite saw heavy losses, triggered by a massive sell-off in semiconductor and artificial intelligence stocks. This downturn suggests that the market's "honeymoon phase" with AI may be coming to a close, replaced by a more critical, data-driven scrutiny of tech valuations.
The Semiconductor Slump: A Canary in the Coal Mine
Semiconductor companies, the primary beneficiaries of the AI infrastructure boom, were at the forefront of the decline. Nvidia, the poster child for the AI era, experienced a sharp drop in valuation, dragging down peers like AMD, ARM, and ASML. The catalyst for this shift appears to be a growing consensus among institutional investors that the breakneck pace of growth seen over the last 18 months is unsustainable in the short term.
The issue is twofold: valuation and demand visibility. Many of these stocks were priced for perfection, leaving no room for even minor misses in earnings or guidance. Furthermore, there are emerging concerns regarding the capital expenditure (CapEx) cycles of major tech firms. While companies like Microsoft and Alphabet continue to pour billions into AI data centers, the timeline for these investments to translate into significant bottom-line growth remains opaque.
From AI Hype to ROI Reality
For the past two years, the market has been fueled by the transformative potential of Large Language Models (LLMs) and Generative AI. However, we are now entering what many call the "show me the money" phase. Investors are no longer satisfied with flashy demos; they want to see how AI is improving margins, reducing costs, or creating entirely new revenue streams for the average enterprise.
"We are witnessing a transition from speculative investment to fundamental evaluation. The AI narrative is shifting from 'what could be' to 'what is actually happening' on the balance sheet," noted a senior market analyst at BlackRock.
The macroeconomic environment adds another layer of complexity. Sticky inflation and the "higher for longer" interest rate environment have increased the discount rate applied to future earnings. For high-growth tech stocks, this mathematical reality makes their current price-to-earnings (P/E) ratios look increasingly precarious.
Geopolitical Headwinds and Supply Chain Realities
Geopolitics continues to cast a long shadow over the tech sector. Recent reports suggesting further U.S. restrictions on high-end chip exports to China have rattled the industry. Given that China remains a critical market for many semiconductor firms, any further decoupling poses a direct threat to global revenue streams. The complexity of the global supply chain means that localized disruptions or policy shifts can have outsized effects on Wall Street's tech giants.
Moreover, the global race for "Sovereign AI"—where nations build their own computing clusters—is creating a fragmented market. While this provides new opportunities, it also increases operational costs and regulatory hurdles for companies that were used to a more unified global market.
Conclusion: A Necessary Recalibration
While the headlines may scream of a tech bloodbath, many experts view this as a healthy and necessary market correction. The "froth" is being washed out, separating the true innovators from those merely riding the AI wave. The long-term trajectory of AI remains positive, as the technology continues to integrate into every facet of the global economy. However, the days of indiscriminate buying of anything with an "AI" label are over. Moving forward, the market will likely reward companies that demonstrate not just technological prowess, but financial discipline and a clear path to monetization.





