

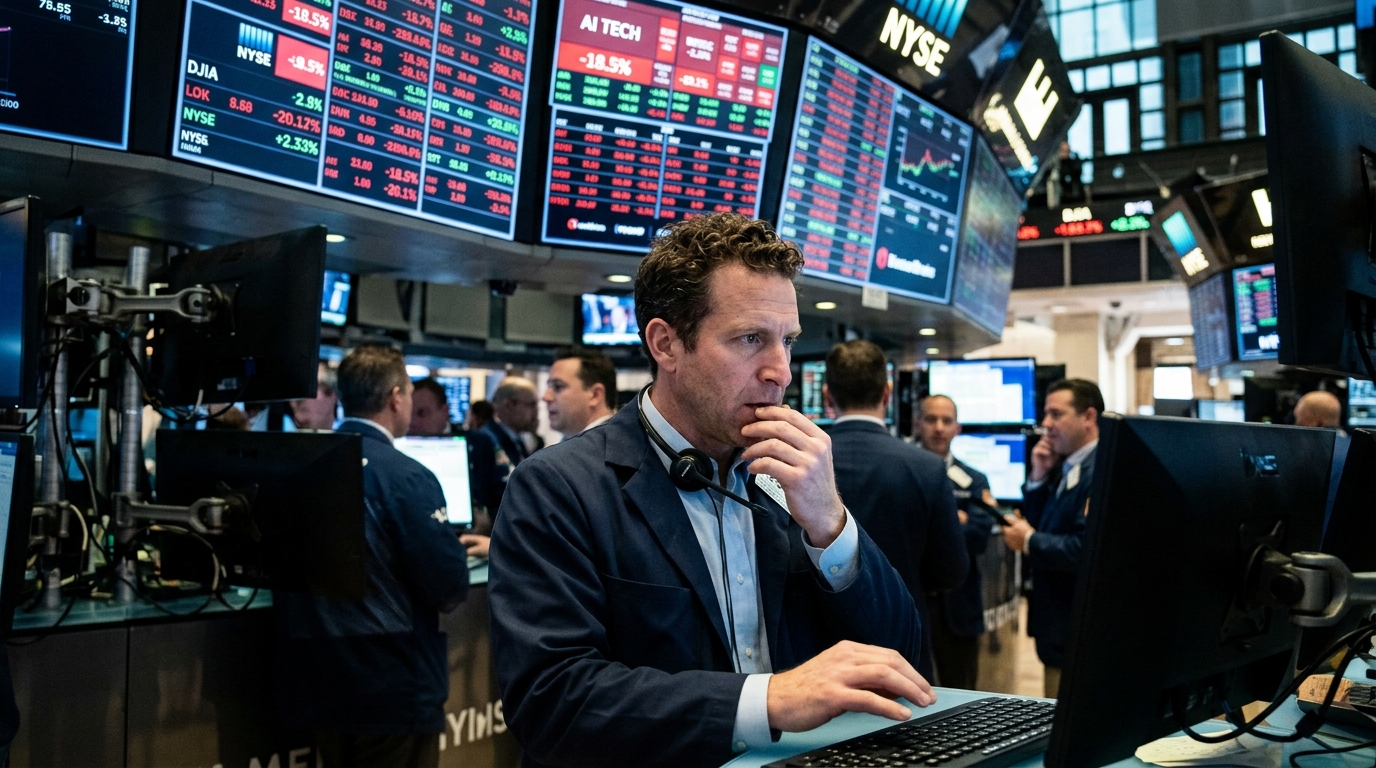
As we navigate the second quarter of 2026, the Artificial Intelligence (AI) investment landscape appears to be entering a new, more sophisticated phase. Following three years of meteoric growth, the recent 20% decline in one of the industry's cornerstones—the leader in AI semiconductors and infrastructure—has sparked jitters across Wall Street. However, for disciplined analysts, this pullback is not the bursting of a bubble, but a necessary 'healthy correction' providing a rare entry point.
Anatomy of the Pullback: Fear vs. Fundamentals
The 20% slide observed since the start of 2026 stems from a convergence of factors. First, the market has begun pricing in intensified competition from Big Tech giants like Google and Amazon, who have now scaled their proprietary custom silicon (ASICs) to reduce third-party dependency. Second, Q1 earnings expectations were set at stratospheric levels, leading even stellar results to be deemed 'underwhelming' by short-term speculators.
'In technology investing, the price you pay determines your return more than the technology itself. 2026 is giving us the chance to buy the future at yesterday\'s prices,' notes a senior Motley Fool analyst.
Yet, the underlying metrics tell a different story. Despite the stock's decline, the demand for AI compute has not wavered. On the contrary, the transition from 'Generative AI' to 'Agentic AI' (autonomous agents) requires even more robust and specialized infrastructure. The stock currently trading at a 20% discount remains the undisputed king of the software stacks that orchestrate these complex systems.
From Training to Inference: The New Revenue Frontier
A primary reason this stock is a 'Screaming Buy' is the paradigm shift occurring in 2026. While 2024 and 2025 were dominated by model 'training,' 2026 is the year of 'inference.' As millions of enterprises worldwide integrate AI into their core operations, the need for chips that execute these processes in real-time is skyrocketing.
- Edge Computing Dominance: The company is aggressively expanding into localized devices, from autonomous vehicles to industrial robotics.
- Software Ecosystem: It’s no longer just about hardware. The company’s AI software subscription services are showing profit margins exceeding 70%.
- Stock Buybacks: With record cash reserves, management has announced a massive buyback program, which will provide a significant tailwind for the share price in the coming months.
The Geopolitics of Artificial Intelligence
We must not overlook that 2026 is the year of 'Sovereign AI.' Nations across Europe and the Middle East are investing billions to establish their own national AI infrastructures to avoid over-reliance on US-based cloud providers. This new cycle of sovereign spending acts as a safety net for this company’s revenue—a factor the market is temporarily ignoring due to macro volatility.
In conclusion, the 20% dip is mere 'noise' in a long-term secular bull trend. For the investor looking toward 2028 and 2030, current valuations offer a margin of safety rarely found in industry-leading firms. History has shown that those who bought during corrections during pivotal technological shifts—much like in 2001 or 2010—were the ones who reaped the most substantial rewards.





