

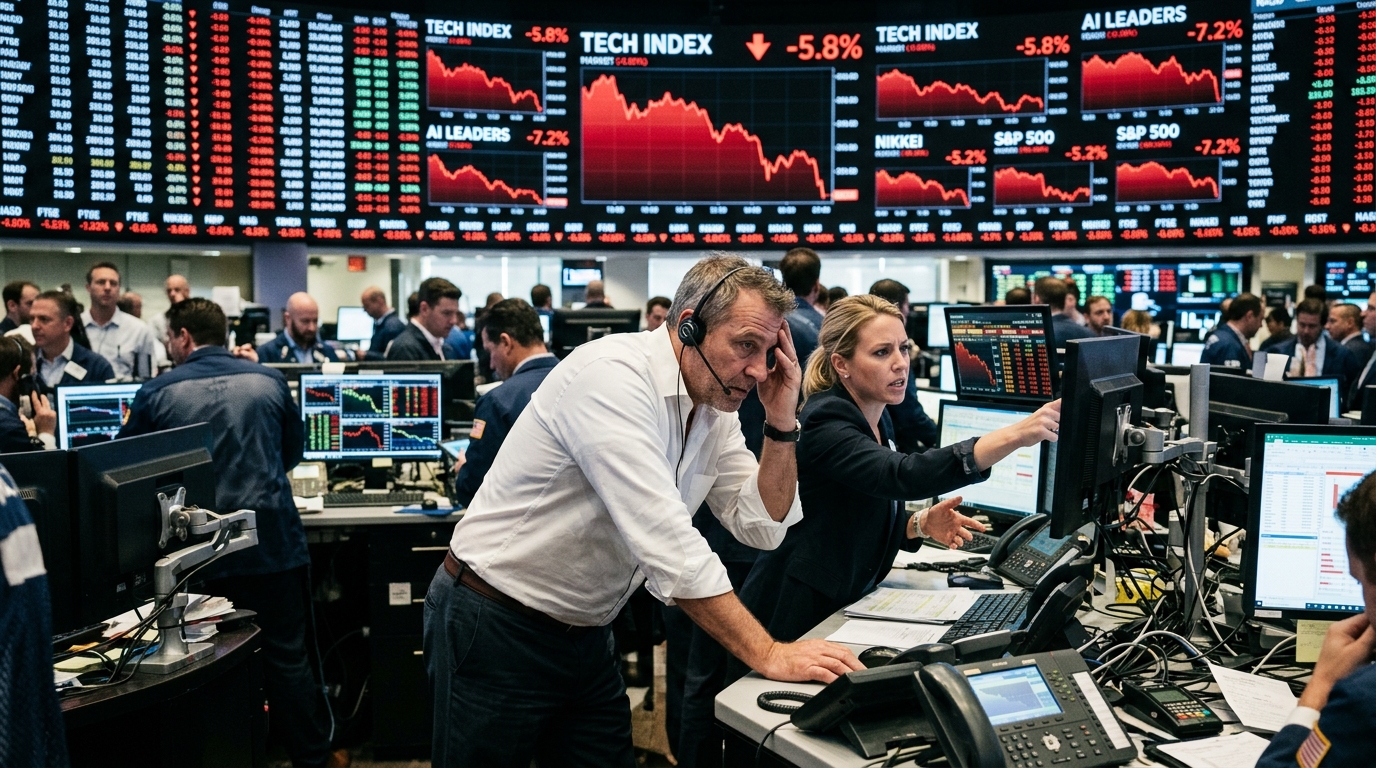
The summer of 2026 finds the global tech landscape at a critical crossroads. After three years of unbridled enthusiasm and investment levels that surpassed any precedent in Silicon Valley history, the era of "easy money" for Artificial Intelligence (AI) seems to be closing for good. Recent financial reports from Big Tech—Microsoft, Alphabet, Meta, and Amazon—reveal a troubling disparity: while capital expenditures (Capex) for AI infrastructure continue to rise at rates of 30-40% annually, the revenue growth directly attributable to these technologies is beginning to show signs of fatigue.
The Productivity Paradox and Shareholder Pressure
The core promise of AI was an explosive increase in productivity that would translate directly into corporate profits. However, integrating Large Language Models (LLMs) into daily business processes has proven more complex and costly than initially forecast. Businesses are now facing the "AI paradox": the cost of operating and maintaining these systems often exceeds the value they generate in the short term.
- Reliance on expensive Nvidia processing units (GPUs) remains the largest drag on balance sheets.
- Energy costs for operating data centers have skyrocketed, squeezing profit margins.
- A shortage of specialized personnel is delaying the implementation of custom AI solutions.
"We are no longer in the experimentation phase. Shareholders are no longer asking 'what can AI do,' but 'when will we get our money back,'" noted a senior analyst at Goldman Sachs.
The Infrastructure Bubble and the Threat of Oversupply
One of the most concerning phenomena is the creation of a potential "infrastructure bubble." Tech giants have invested hundreds of billions in building massive data centers, anticipating a demand that may not materialize to the extent expected. If the adoption of AI services by end-users and businesses does not accelerate dramatically over the next 12 months, the market will face massive excess capacity, leading to capital impairment.
In Europe, the situation is further complicated by the full implementation of the AI Act. Strict regulations on transparency and data security add an extra layer of compliance costs, which American firms are struggling to absorb. This has led to a temporary retreat of investment on European soil as companies wait to see how the legal landscape settles.
From Generative AI to "Practical" AI
Despite current pessimism, the market is not collapsing; it is maturing. We are observing a shift from general models that do "everything" toward specialized, smaller, and more efficient models (SLMs) targeting specific sectors such as medical diagnostics, legal research, and supply chain management. These models require less computing power and offer a clearer ROI.
The current retreat in revenue and investor doubt represents a healthy correction. As happened with the internet in the early 2000s, the technology is real and transformative, but its financial valuation ran much faster than its actual utility. The next phase of AI will be judged not by the promises of CEOs, but by the spreadsheets of Chief Financial Officers.





