

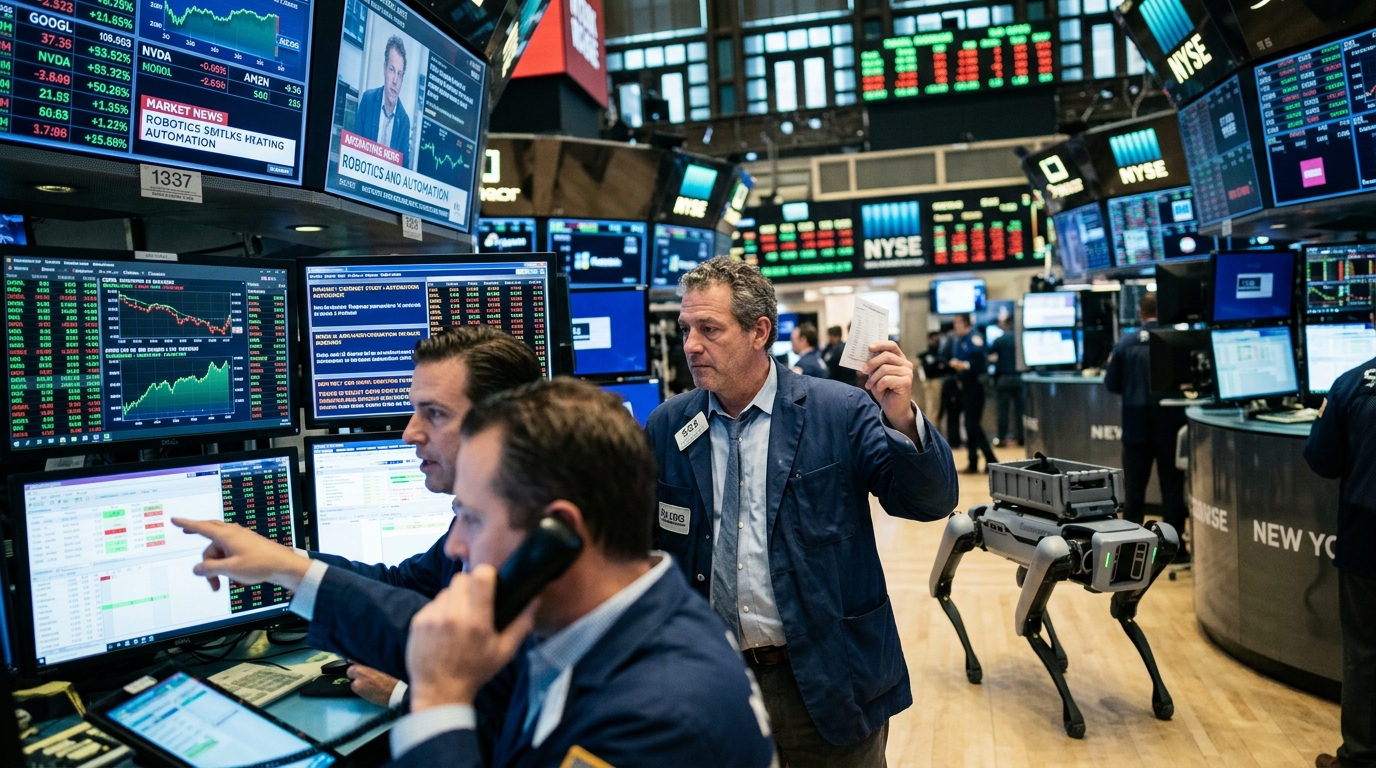
As we navigate the summer of 2026, the global economy stands at the threshold of a structural shift unseen since the first Industrial Revolution. The robotics market, once confined to heavy automotive assembly lines, has ballooned into a $200 billion ecosystem. What we are witnessing is not merely the addition of more machines to factories, but the full integration of Artificial Intelligence into physical embodiments, creating a new class of "workers" that do not tire, do not strike, and learn at an exponential rate.
The Convergence of AI and Physicality
The explosive growth of this market is driven by one critical factor: the convergence of Large Language Models (LLMs) with robotic locomotion. Until 2024, robots were programmed to perform specific, repetitive tasks. Today, in 2026, "Embodied AI" allows machines to understand natural language and adapt to unpredictable environments. This breakthrough has opened the doors for robotics to penetrate the service sector, healthcare, and logistics, where flexibility is paramount.
According to recent data, the service sector now accounts for 40% of the total market, with elderly care robots and autonomous delivery units becoming a common sight in the metropolises of Asia and North America. Europe, while moving at a slightly slower pace, is investing heavily in "Collaborative Robotics" (Cobots), where humans and machines share the same workspace with absolute safety.
Humanoid Robots: From Lab to Production Floor
The most striking segment of this $200 billion market is humanoid robotics. Companies like Tesla with Optimus Gen 3 and Figure AI have managed to drive down the production cost of a humanoid unit to below $30,000. This tipping point makes purchasing a robot more economically viable than employing an unskilled worker over a three-year period, factoring in maintenance and energy costs.
Their deployment in next-generation Gigafactories has already led to a 35% increase in productivity. However, challenges remain regarding battery autonomy and fine motor skills. Investments in new actuators and tactile sensors have spawned a multi-billion dollar secondary market, primarily benefiting Japanese and German high-tech firms.
Geopolitics and the Battle for Supremacy
Robotics is not just an economic issue; it is a matter of national power. China, facing an acute demographic crisis, has set a goal to become the global leader in robotics by 2030. With massive state subsidies, Chinese firms are flooding the market with affordable yet highly capable units, triggering reactions from the US and the EU. Recently imposed tariffs on Chinese robots mirror the semiconductor trade wars, highlighting that whoever controls the "workforce of the future" controls the global supply chain.
Europe, through the AI Act and new machinery safety regulations, is attempting to balance innovation with job protection. The Old Continent's strategic autonomy now depends on its ability to produce its own robotic systems, reducing reliance on imports of critical components from the East.
Social Costs and the Redistribution of Wealth
Despite the economic euphoria in the markets, the question of employment remains urgent. The automation of 2026 threatens not only manual laborers but also lower-level management, as robots are integrated into decision-making systems. Discussions regarding Universal Basic Income (UBI) or a "robot tax" have returned forcefully to the G20 agenda.
Proponents of the technology argue that robotics will liberate humans from the "3Ds"—Dull, Dirty, and Dangerous jobs—creating new roles in design, maintenance, and ethical oversight. However, the speed of this transition is such that educational systems worldwide are struggling to keep pace. The $200 billion market is a promise of abundance, but also a warning of the need for a new social contract.





