

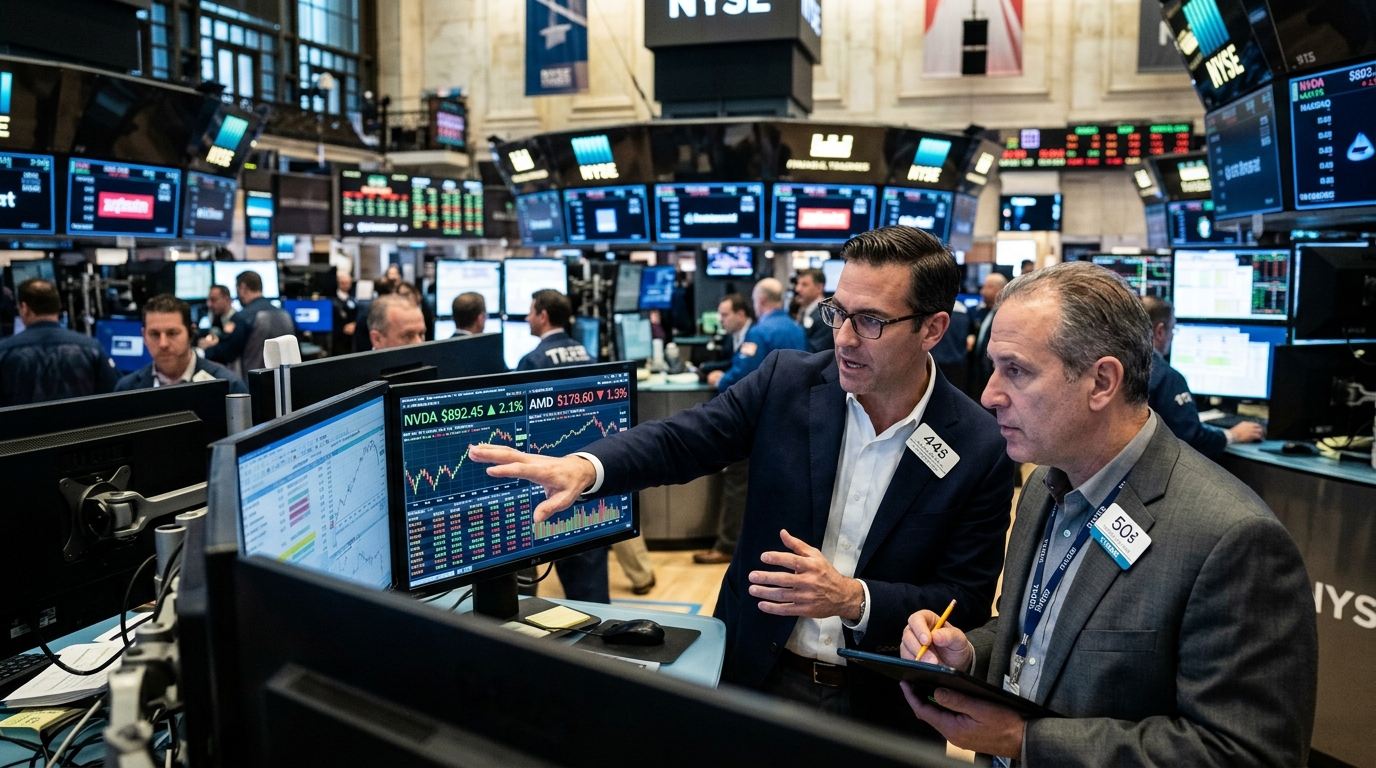
As we navigate the summer of 2026, the global economic landscape continues to be defined by a single factor: computational power. The battle between Nvidia and AMD is no longer just a competition between two chipmakers for gamers; it is an existential clash for dominance over the infrastructure of human intelligence itself. With Nvidia’s market capitalization hovering at stratospheric levels and AMD striving to establish itself as the only credible alternative, investors face a critical question: Is Nvidia undervalued despite its massive run-up, or is AMD overvalued in its attempt to catch up?
The Nvidia Empire: Beyond the Multiples
For many Wall Street analysts, Nvidia is no longer a semiconductor company, but a provider of integrated AI ecosystems. The success of the Blackwell architecture, released two years ago, and the transition to the new generations of chips we see today in 2026, have proven that the company's advantage lies not just in hardware. The CUDA software remains the "iron curtain" preventing customers from migrating to other platforms.
When examining whether Nvidia is undervalued, we must look at the PEG (Price/Earnings-to-Growth) ratio. Despite a P/E ratio that looks terrifying to the average investor, Nvidia’s explosive revenue growth often makes its valuation more attractive than it appears at first glance. Demand for data centers shows no signs of slowing down, as governments worldwide are now investing in "AI sovereignty," building their own infrastructures to avoid dependence on American Big Tech.
AMD: The Eternal Challenger and the Open Source Bet
On the other hand, AMD, under the leadership of Lisa Su, has followed a different strategy. The Instinct MI300 accelerator series and its successors have managed to gain significant market share, primarily due to their open-source approach (ROCm). Major cloud providers like Microsoft and Meta are desperate for a second supplier to break Nvidia’s monopoly and reduce their costs.
However, AMD’s valuation is often based on future expectations rather than current Nvidia-level profitability. If AMD is considered overvalued, it is because the stock market is pricing in a success that has not yet fully materialized in terms of profit margins. While Nvidia enjoys margins reminiscent of a luxury software company, AMD is still struggling with production costs and the need to offer lower prices to entice customers.
The Bubble That Didn't Burst (Yet)
In 2026, the "AI bubble" debate has shifted. We are no longer asking if the technology is useful—that has been proven—but whether the capitalization of these companies can be sustained when the growth rate of data centers inevitably slows down. Nvidia has the first-mover advantage, but AMD has the advantage of flexibility.
- Nvidia controls approximately 90% of the high-end AI chip market.
- AMD offers a more cost-effective solution, which becomes attractive as corporate AI budgets begin to rationalize.
- Geopolitical tensions surrounding Taiwan remain the biggest risk for both companies, as both rely on TSMC for production.
In conclusion, the answer to whether one is undervalued and the other overvalued depends on the investor's horizon. If you believe that AI is an infrastructure that will continue to expand for the next decade, Nvidia may still be cheap. But if you believe the market will seek balance and price competition, AMD is the company with the greatest upside potential, provided it can bridge the software gap.
"In the age of AI, the chip is no longer a component; it is the currency of power. And like any currency, its value is determined by trust in the future."





