

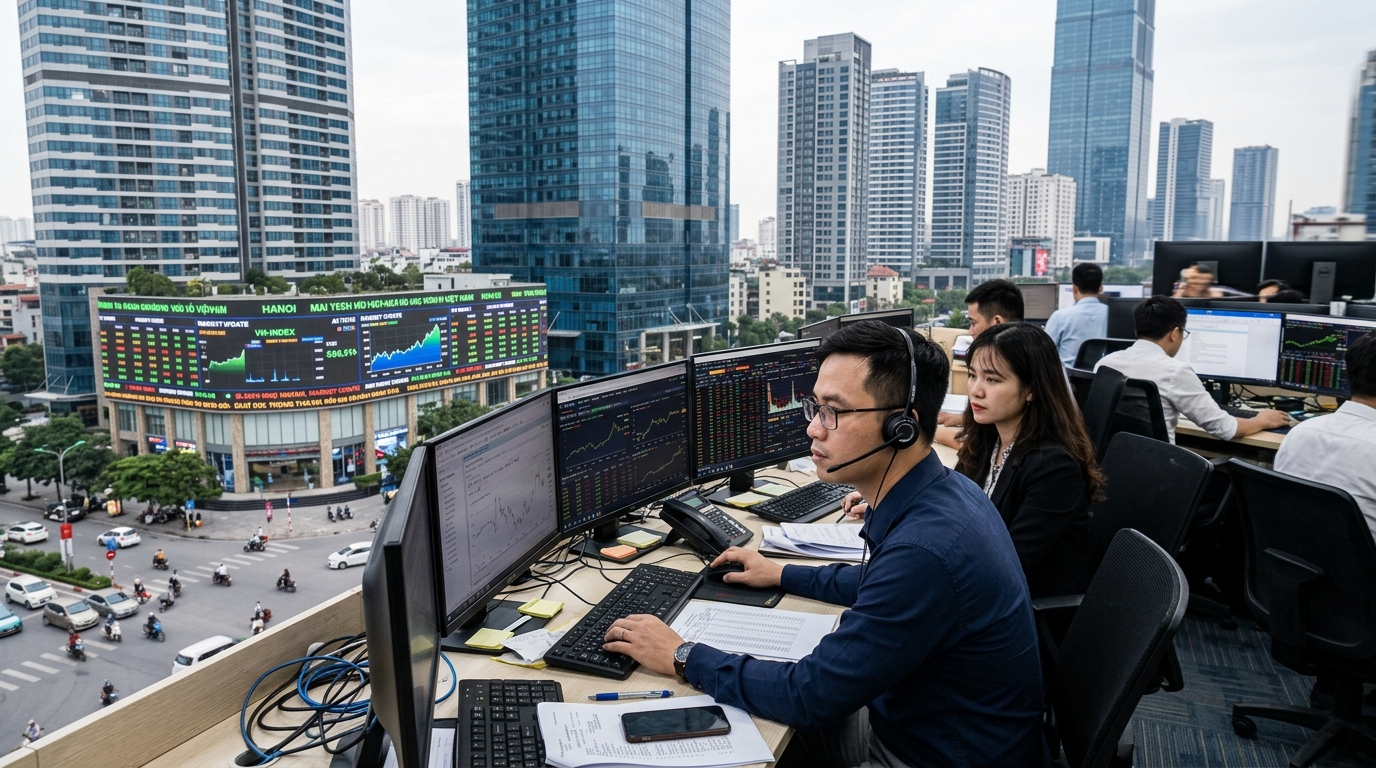
As we navigate through June 2026, the financial sector is undergoing its most radical transformation since the invention of the credit card. What we once called "digital banking"—the simple migration of banking tasks from the physical counter to a mobile screen—is now considered legacy. Today, the industry is pivoting toward "AI Banking," where software doesn't just execute commands; it predicts needs, manages risks, and acts as an invisible, omnipresent financial co-pilot.
Recent reports from Vietnam, a nation rapidly emerging as a regional tech powerhouse, highlight a global trend: emerging economies are leapfrogging traditional development stages, moving straight to AI-first solutions. In Hanoi and Ho Chi Minh City, banks are no longer investing in physical branches but in Large Language Models (LLMs) capable of analyzing the creditworthiness of a farmer or a small business owner in seconds, utilizing alternative data points that traditional banking would typically ignore.
Hyper-Personalization: The New Standard
The defining difference between digital and AI banking lies in proactivity. While digital banking allowed you to check your balance, AI banking warns you that, based on current spending habits, you won't be able to cover next month's mortgage, automatically suggesting a budget adjustment or a pre-approved micro-loan with favorable terms.
This hyper-personalization transforms the bank from a cold custodian of deposits into a life partner. AI systems analyze thousands of parameters—from consumer habits to global market fluctuations—to provide real-time advice. For the average user, this means less financial stress. For the bank, it translates into increased customer loyalty and new revenue streams from value-added services.
Security and the Fight Against Fraud
In a world where cyberattacks are becoming increasingly sophisticated, traditional security measures like passwords and One-Time Passwords (OTPs) are failing. AI banking introduces "behavioral biometrics." The system doesn't just recognize your fingerprint; it recognizes how you hold your phone, the speed at which you type, and your unique movement patterns. If an intruder attempts to access your account, the AI detects the anomalous behavior before the login process is even completed.
Furthermore, Anti-Money Laundering (AML) efforts have reached a new dimension. AI systems can identify suspicious transaction networks spanning dozens of countries and thousands of accounts—a task that would take human analysts weeks to complete. This drastically reduces operational costs, allowing banks to offer more competitive interest rates and lower fees.
The Vietnam Case: A Lesson for the West
It is fascinating to observe why countries like Vietnam are leading the charge. Unencumbered by the "legacy systems" that plague European and American banks, financial institutions in Southeast Asia are building their infrastructure directly in the cloud with integrated AI. The adoption of QR payments and digital wallets is nearly universal there, creating a massive data lake that fuels increasingly accurate algorithms.
The West, by contrast, is struggling with a regulatory labyrinth. While data protection is critical (as seen in the EU AI Act), there is a growing risk that over-regulation might make Western banks less innovative than their Asian counterparts. Balancing ethical AI usage with global economic competitiveness will be the defining challenge of the coming years.
The Future of Work in Finance
Naturally, this transition is not without its hurdles. The automation of core banking functions raises significant questions about the future of the financial workforce. We are already seeing a convergence of roles: the bank employee of the future must be more of a technology and ethics consultant than a mere processor of applications. Human touch will remain invaluable for complex decisions—such as financing a major infrastructure project or crisis management—but the day-to-day operations will belong to the algorithms.
In conclusion, the shift to AI banking is more than a technological upgrade. It is a philosophical shift in how we perceive financial trust. The bank of 2026 is no longer a building or an app; it is an intelligent service that flows seamlessly through our daily lives.





