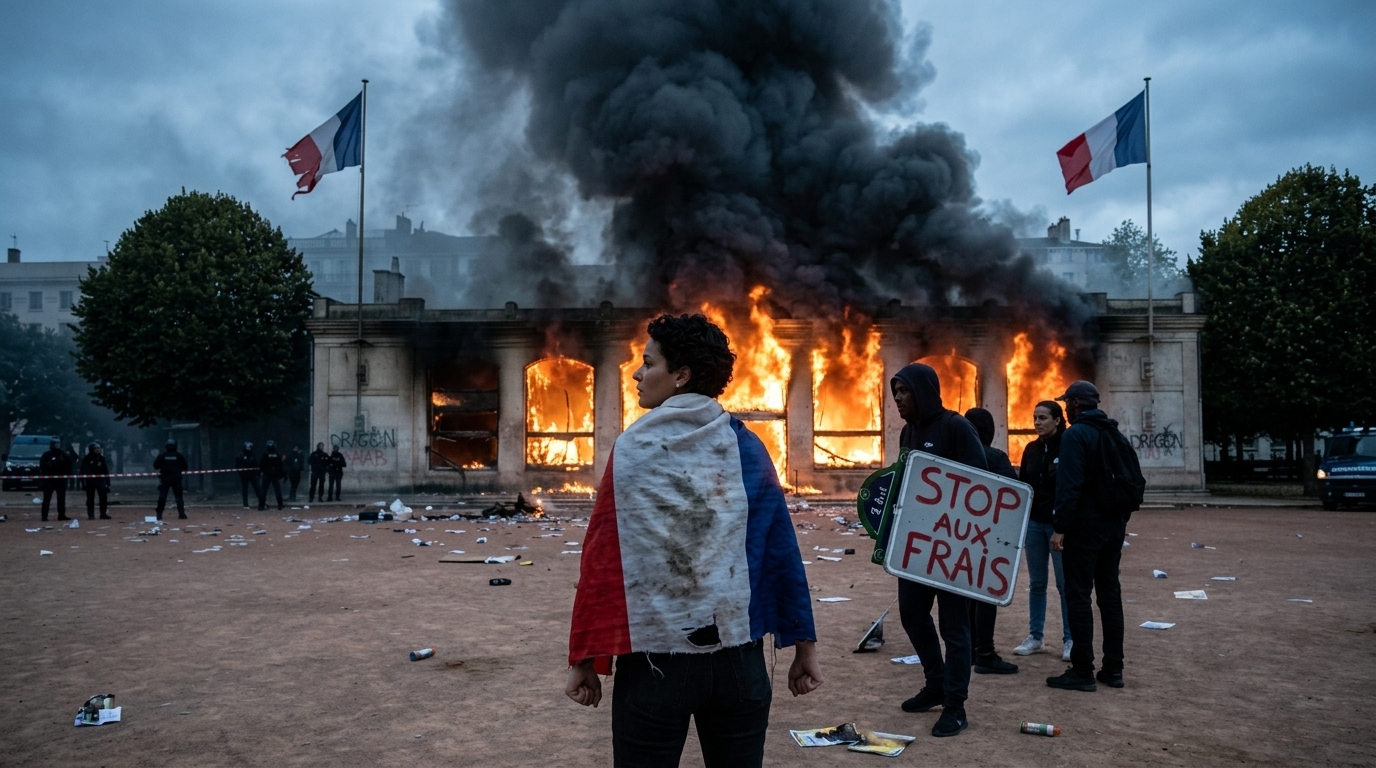
France is grappling with a multi-layered crisis that threatens to destabilize the world’s seventh-largest economy. As nationwide protests over the cost of living escalate into riots, the nation nears a make-or-break moment for its public debt, which has reached a record $4 trillion, or 119% of GDP.
Market Pressure and Political Gridlock
French bond yields have surged to their highest levels in 24 years, flashing warning signs not seen since the 2011 eurozone debt crisis. Investors are showing deep distrust, driven more by political instability than pure economics. With far-right and far-left candidates leading polls for the upcoming spring presidential election, markets fear that neither side will implement the painful reforms needed to rein in the deficit.
Pensions vs. Education
Analysts, including Mujtaba Rahman of Eurasia Group and Nobel laureate Paul Krugman, point to a profound structural imbalance. While education spending exceeds the EU average, more than a quarter of that funding is consumed by teacher pensions. This has resulted in years of underinvestment in public schools, fueling anger among students protesting run-down classrooms. Krugman argues that France is effectively subsidizing its older population at the expense of the youth.
The Critical Tuesday Vote
Prime Minister Sébastien Lecornu has proposed a 2027 budget aimed at narrowing the deficit to 5% from 5.4%. A critical first vote in the National Assembly is scheduled for Tuesday. If the government fails to pass the budget, borrowing costs could explode. Analysts warn that France might be forced to seek assistance from the International Monetary Fund and the European Central Bank—a scenario described as a potential 'humiliation' for the global power.