

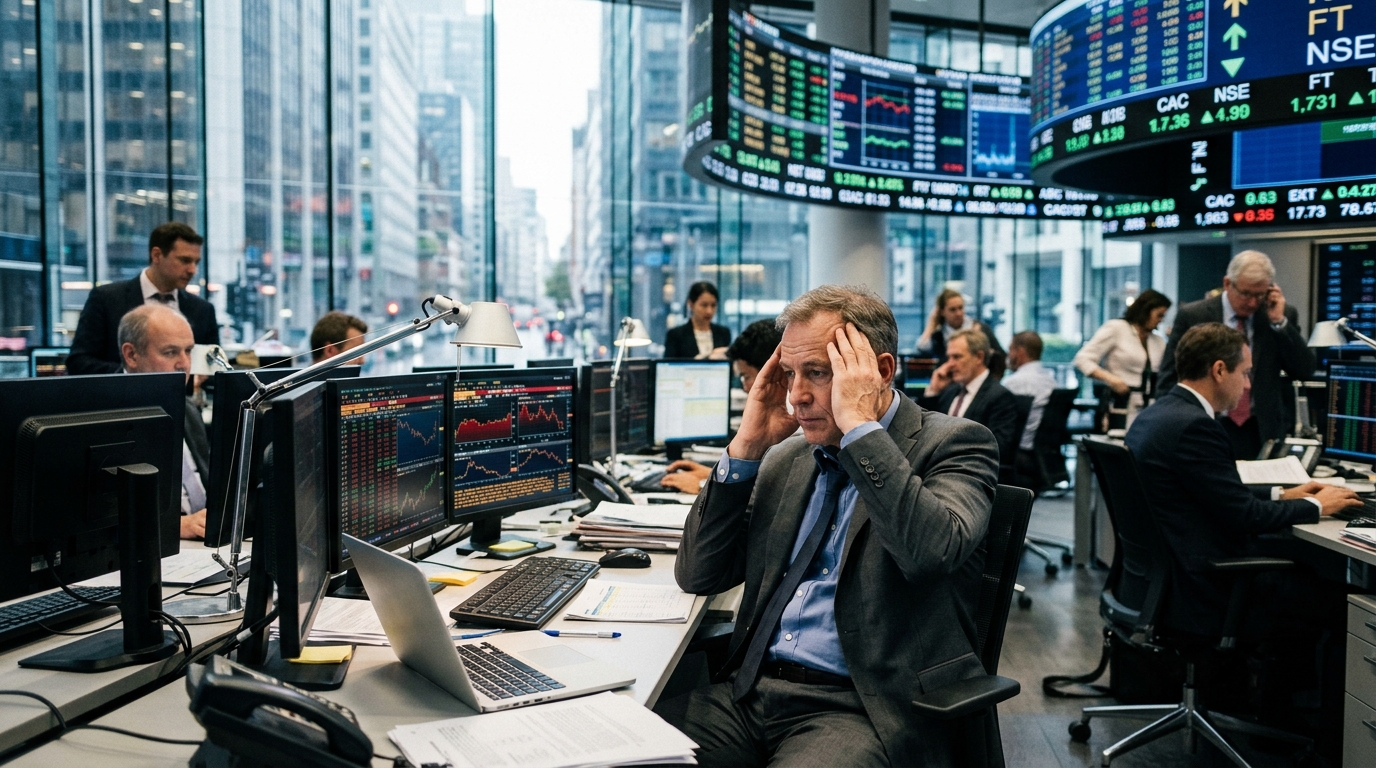
The image of imposing banking halls filled with armies of clerks and paper-laden desks is fading into history. Today, the corridors of Wall Street and the City of London echo with a different reality: that of algorithms and automated efficiency. As we progress through 2026, the banking sector is in the throes of a historic restructuring. Massive layoffs announced by giants like Citigroup, UBS, and Goldman Sachs are not merely a cyclical phenomenon, but the onset of a structural mutation fueled by Artificial Intelligence (AI).
The Digital Guillotine of Jobs
The numbers are stark. In the last year alone, the world's largest banks have eliminated over 60,000 positions. While management often cites a "challenging macroeconomic environment" and high interest rates, the reality behind closed boardroom doors is the aggressive adoption of Generative AI. This technology is no longer confined to simple back-office tasks. AI is now drafting legal documents, analyzing credit risks in seconds, and executing complex trading strategies that previously required teams of seasoned analysts.
Citigroup's case is emblematic. Under the "Bora Bora" restructuring plan, the bank announced the cut of 20,000 jobs, with CEO Jane Fraser stating clearly that simplifying processes through technology is the only path to sustained profitability. However, the question remains: Is AI the perpetrator or simply the tool of a broader deconstruction of the labor model?
From Tellers to Algorithms: The Shift in Value
AI in banking operates across three distinct levels. First, in customer service, where sophisticated chatbots have replaced 80% of basic inquiries, rendering traditional call centers largely obsolete. Second, in the middle-office, where compliance and anti-money laundering (AML) checks—fields that once employed thousands—are now handled by machine learning systems with negligible error rates. Third, in investment banking, where AI can "read" thousands of pages of financial reports and identify investment opportunities faster than any junior banker.
- Automation of Cognitive Tasks: AI isn't just replacing hands; it's replacing minds by taking over report writing and data synthesis.
- Operational Cost Reduction: Banks are targeting 20-30% expense reductions through deep digitalization.
- Personalization at Scale: The ability to offer tailored financial products without human advisors reduces the need for physical branch staffing.
"We aren't just seeing a headcount reduction; we're seeing a renegotiation of what it means to be a banker," says a leading Frankfurt-based analyst. "The bank of the future is a technology company that happens to hold a banking license."
The Social Dimension and the Reskilling Mandate
This transition is far from bloodless. Concerns about "structural unemployment" in the financial sector are mounting. Mid-career professionals face the specter of skill obsolescence. Reskilling is no longer a luxury but a survival mandate. Banks are investing billions in training programs to pivot their workforce toward AI literacy, yet it is clear that there won't be a place for everyone in this new digital landscape.
Furthermore, geopolitical instability and inflation are pressuring banks to fortify their balance sheets. In this context, AI offers an "easy fix" to maintain shareholder dividends. Yet, ethical questions loom: Who is responsible for a flawed lending decision made by an algorithm? And how is transparency ensured when decisions are buried within "black box" code?
Conclusion: A World Without Bankers?
Artificial Intelligence is not the sole culprit for the layoffs, but it is the catalyst accelerating a process that began after the 2008 crisis. Banks are transforming into platforms. While low- and mid-skill roles are evaporating, new positions are emerging for data engineers, AI ethics specialists, and cybersecurity analysts. The challenge for society and governments is to ensure that technological progress does not lead to a new era of social exclusion, but rather to a more equitable and efficient financial system.





