

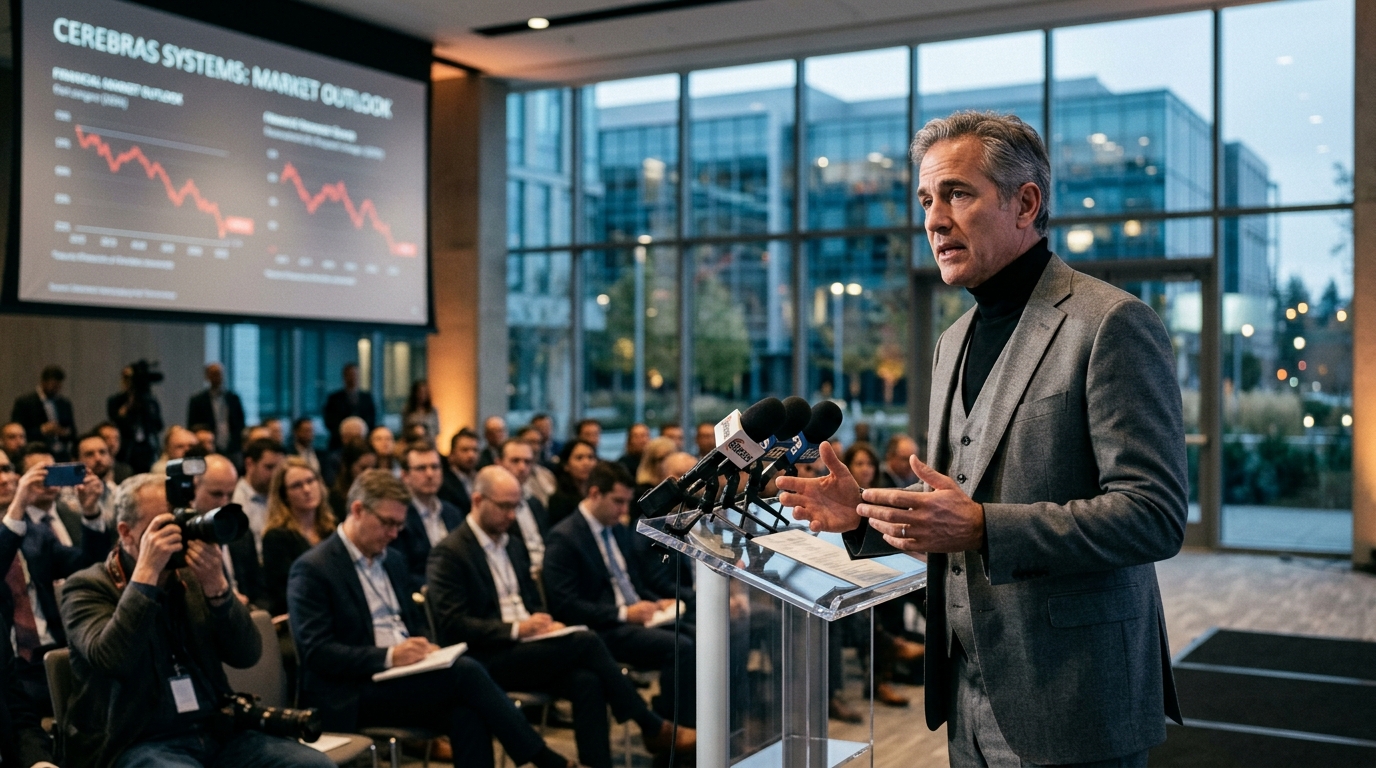
The earnings debut of Cerebras Systems, the company that promised to disrupt the AI processor status quo with its gargantuan chips, did not unfold as investors had hoped. Following its highly anticipated IPO, the company's first official financial report was met with a sharp drop in share price, as its profit margins significantly lagged behind those of rivals like NVIDIA and AMD. The Cerebras case highlights a fundamental truth in the AI era: technical superiority on paper does not always translate into economic efficiency in practice.
Size Isn't Everything: The Wafer-Scale Engine Challenge
Cerebras has built its reputation on the Wafer-Scale Engine (WSE), a processor the size of an entire silicon wafer. While traditional processors are cut from a wafer into hundreds of small pieces, Cerebras uses the entire surface to create a single, massive supercomputer on a chip. This approach allows for lightning-fast communication between cores, drastically reducing the latency observed in systems that interconnect many smaller processors.
However, manufacturing such a behemoth comes with immense costs. Production yield—the percentage of chips produced without defects—is much harder to control on a processor of this scale. According to the earnings report, Cerebras' gross margins remain below 50%, at a time when NVIDIA enjoys margins approaching 75%. This gap is not just a number; it is evidence that Cerebras is spending significantly more to produce the same computational power that its competitors produce more economically.
The Shadow of NVIDIA and Market Competition
The AI semiconductor market is entering a phase of maturation. If 2024 and 2025 were the years of the "land grab," where companies bought any chip available, 2026 is the year of efficiency. Customers, from Microsoft to OpenAI, are now scrutinizing Total Cost of Ownership (TCO). Cerebras claims its systems are more efficient for training Large Language Models (LLMs), but investors worry the company is being forced to slash prices to gain market share, further squeezing profits.
- NVIDIA's dominance with the CUDA software stack remains the biggest hurdle for any newcomer.
- AMD has managed to improve its own margins with the MI300 series, positioning itself as the clear alternative.
- Cerebras relies heavily on a few large customers, which creates significant revenue volatility.
"Cerebras' technology is an engineering marvel, but the stock market doesn't buy marvels; it buys scalable profits," noted a senior Wall Street analyst.
The Road Ahead: Can Cerebras Bounce Back?
The stock drop following the earnings debut is a strong signal, but it doesn't necessarily spell the end. Cerebras possesses a unique architecture that could prove indispensable for the next generation of AI models requiring even greater data coherence. However, to convince the market, it must prove it can optimize its supply chain and reduce the manufacturing costs of its WSE-3 chips.
Furthermore, the company must expand its software ecosystem. Developers are accustomed to NVIDIA's tools, and transitioning to an entirely different architecture requires time and capital. If Cerebras fails to improve its margins in the next two quarters, it risks remaining a niche player in a market that favors giants capable of mass-producing chips cheaply and efficiently.





